Trading Apologist
The Weekly Market Digest · Sunday, September 13, 2026
Hi everyone,
I hope you had a good weekend and got some time to step away from the screens. Before the next trading week gets going, I want to take a quick look back at everything we covered this past week.
The week in brief
It was a dense week. The macro picture dominated a lot of the conversation, with August CPI printing a hot core, hike odds climbing to 80%, and yields somehow falling anyway, while PPI added its own wrinkle with a soft core but a warm pipeline. We spent a good amount of time on the AI capex trade, looking at falling token prices, what Taiwan chip filings are actually telling us about demand, and a cleaner framework for judging the trade through the lens of work, intensity, and scarcity rather than headline spend numbers. On the earnings side, we had 6 reporters this week and a 50% beat rate, with the tape treating reporters poorly overall and an average price reaction of negative 4.9 percent. Consumer Defensive held up best on a beat rate basis, though even that sector averaged a negative 5.8 percent reaction, and Tech ex semis was the weakest sector at 0 percent beats. The other thing to watch is AI sentiment: Amodei's essay calling on the industry to slow frontier development landed with backing from Altman and Musk, and while nothing in it cuts chip or capex demand directly, how the market receives it at Monday's open will set the tone for the AI trade this week.
It was a dense week. The macro picture dominated a lot of the conversation, with August CPI printing a hot core, hike odds climbing to 80%, and yields somehow falling anyway, while PPI added its own wrinkle with a soft core but a warm pipeline. We spent a good amount of time on the AI capex trade, looking at falling token prices, what Taiwan chip filings are actually telling us about demand, and a cleaner framework for judging the trade through the lens of work, intensity, and scarcity rather than headline spend numbers. On the earnings side, we had 6 reporters this week and a 50% beat rate, with the tape treating reporters poorly overall and an average price reaction of negative 4.9 percent. Consumer Defensive held up best on a beat rate basis, though even that sector averaged a negative 5.8 percent reaction, and Tech ex semis was the weakest sector at 0 percent beats. The other thing to watch is AI sentiment: Amodei's essay calling on the industry to slow frontier development landed with backing from Altman and Musk, and while nothing in it cuts chip or capex demand directly, how the market receives it at Monday's open will set the tone for the AI trade this week.
The Weekly Alpha
The week's flagship posts: the market recap, the live calls, and the watchlist review.
Weekly Trade Recap - 9/8 - 9/11 · Sep 12
This week ran to eight trades across eight names, and most of it was housekeeping: cutting two protective put hedges I should have closed earlier, buying back covered calls, and taking profit in two spots. Highlights include rolling TE calls out and up for a net credit, adding to IBM and ENTG calls, and selling another 25% of CRCL at a 54.81% gain for a blended 62.24% across the half now sold. The week was about clearing drag off positions I want to stay long in.
Weekly Market Prep Zoom - 09.07.26 · Sep 8
On the Weekly Market Prep call we covered platform updates including deprecated indicator versions replaced by Deviation Bands and Adaptive Mean Reversion, a major Money Flow engine upgrade, and new AI Trade Desk features including Switch Pair, Spread Pair, and Rotation Group. On markets, two weeks of institutional indecision in Money Flow mirrors the tape, with the base case being a bit more chop into a September low near the 7600 gap on the S&P 500, possibly on the PPI and CPI prints. The Nasdaq is showing relative strength, DRAM and SMH are leading, and crypto is building bottoming structure.
Markets & Macro
The bigger picture across rates, commodities, and the tape.
Token Prices Are Falling. The AI Capex Math Assumes They Don't Matter · Sep 8
More than $700 billion of hyperscaler capex and near-trillion-dollar lab valuations rest on one assumption: that demand for compute stays close to limitless however cheap tokens get. A blended index of what buyers pay per million tokens has already dropped more than 50% from its late-May peak to about $0.97, with proprietary models cutting alongside open-source ones. Three cracks in the bull case: scaling could slow, task length could stop growing, and many real problems have no shortcut a model can learn.
Earnings Up 29%, Multiples Down 13%: Why the S&P 500 Got Cheaper While Rising · Sep 13
The S&P 500 is up 11.9% this year while earnings grew 29.2%, and the multiple actually contracted 13.4%, putting the index below its 5-year average P/E. Every sector with big earnings growth got cheaper: Technology grew earnings 59.6% and lost 22.8% of its multiple, and NVDA's revenue is up 106% year over year while the stock is flat since May. The market is not refusing to pay for earnings it has; it is refusing to pay for earnings it does not have yet, and the doubt sits in the mega caps writing the capex checks, not the companies cashing them.
August CPI: Core Ran Hot, Hike Odds Hit 80%, and Yields Fell Anyway · Sep 11
August CPI matched at the headline (0.4% monthly, 3.4% annual) but core ran hot at 0.3% against a 0.2% expectation, driven by hotels, airfares, and phone plans. Kalshi moved the odds of a 25 bps hike next Wednesday to 80%, the 2-year spiked toward 4.66%, and the 10-year briefly touched 5.00% before both reversed lower. The long end is rallying into the hike because oil dropped nearly 4% on an IEA report cutting 2026 demand by 2.5 million barrels per day, which is pulling yields and equities in opposite directions from what you might expect.
Also this week
Sector Relative Strength
Week of September 04 · % change vs prior week's close
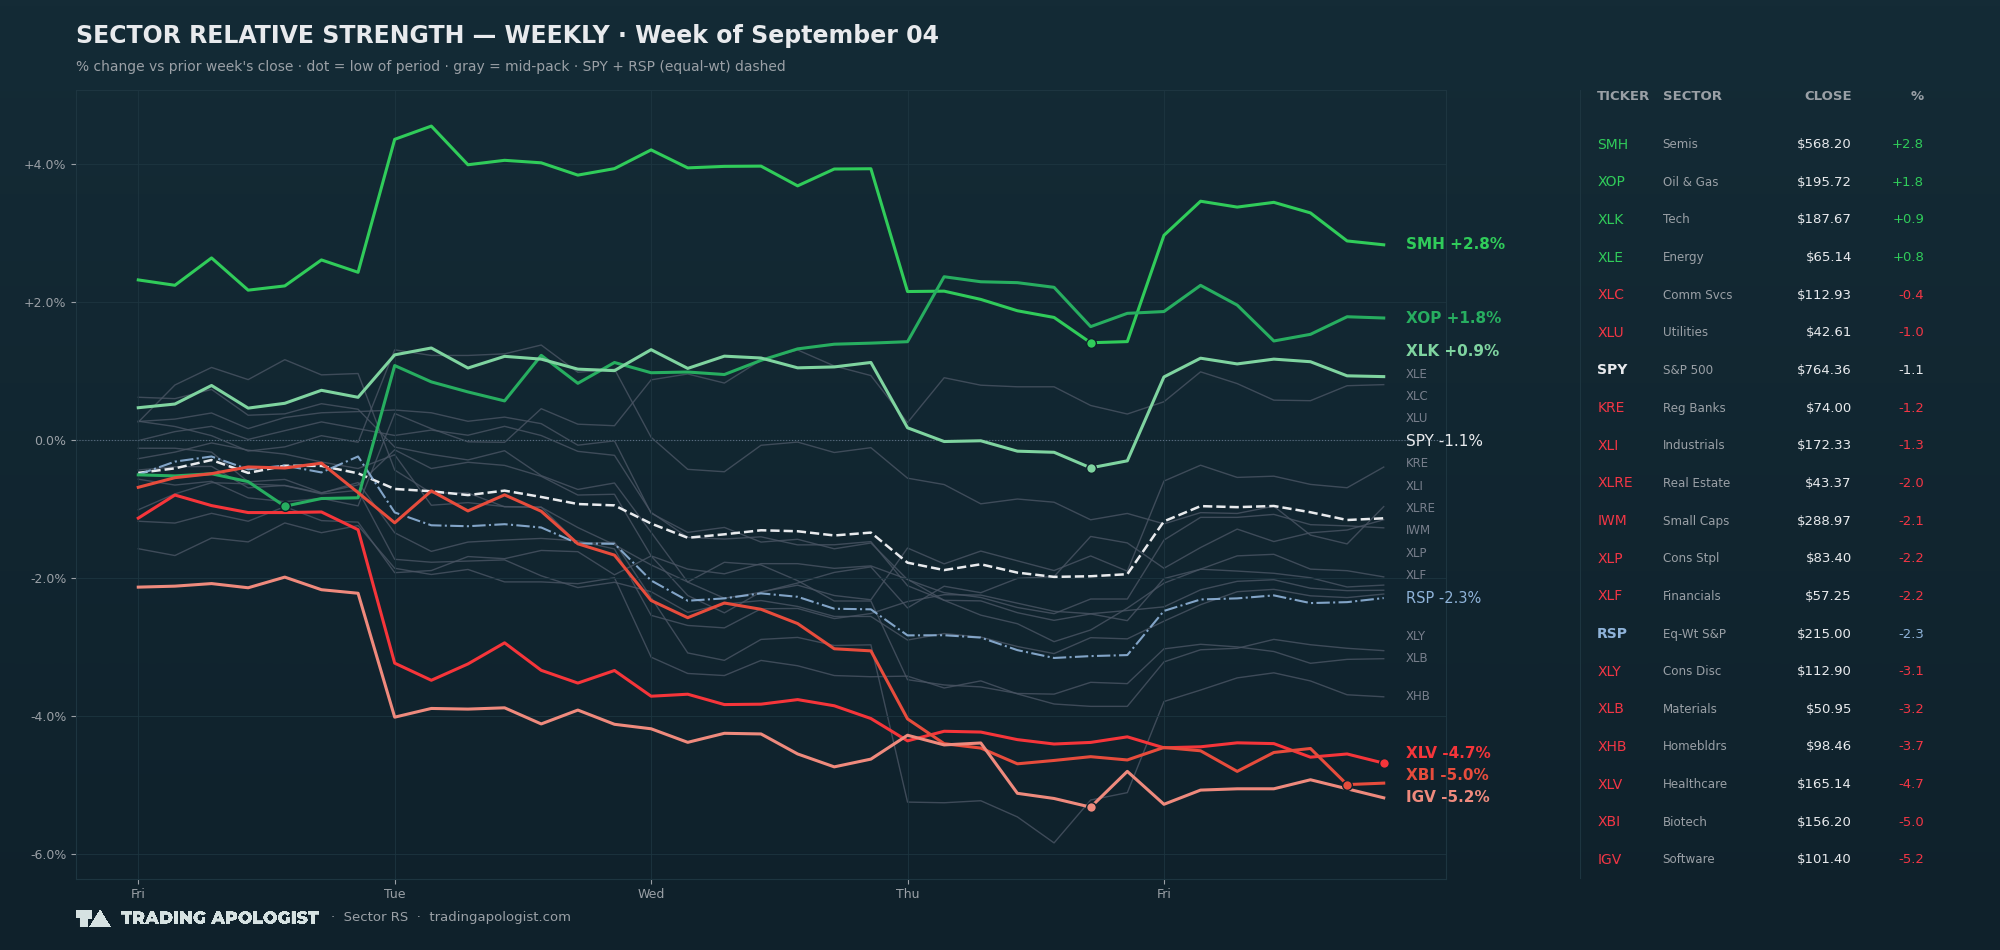
Semiconductors (SMH)+2.82%
Oil & Gas E&P (XOP)+1.76%
Technology (XLK)+0.91%
Energy (XLE)+0.80%
Comm Services (XLC)-0.40%
Utilities (XLU)-0.97%
Regional Banks (KRE)-1.16%
Industrials (XLI)-1.28%
Real Estate (XLRE)-1.99%
Small Caps (IWM)-2.11%
Cons Staples (XLP)-2.18%
Financials (XLF)-2.24%
Cons Discretionary (XLY)-3.06%
Materials (XLB)-3.17%
Homebuilders (XHB)-3.73%
Healthcare (XLV)-4.69%
Biotech (XBI)-4.98%
Software (IGV)-5.19%
S&P 500 (SPY)-1.14%
Equal-weight S&P (RSP)-2.29%
Market Recaps
Every market recap from the week in one place: the daily and morning notes plus the weekly recap.
Wednesday Daily Market Recap - September 9th, 2026
Community & Tool Updates
Indicator releases, new tools, events, and community happenings.
AI Trade Desk Guide: Platform & Features Overview · Sep 12
Miles recorded the first full walkthrough of the AI Trade Desk, covering where everything lives and how the pieces connect day to day. The tour goes through the Deep Read, asset chats, side-by-side comparisons, tracked assets and alerts, Supercharts with liquidation levels and options walls, pair trading and rotation, and the journal. If you have been using the desk without a proper orientation, this is the one to watch.
Indicator Guide: TA Gann Swing · Sep 13
The TA Gann Swing Indicator guide is up, covering the methodology that got me started in technical analysis. The video walks through the swing overlay, trend breaks, the three-bar reversal signal, the seven-bar count rule, bar type labels, seasonal Gann dates, and the filters worth using, all demonstrated on BTC. The three-bar signal is my favorite feature in the suite because it fires once per structural turn and tends to appear right before a pivot or consolidation.
Indicator Guide: TA Adaptive Levels · Sep 9
TA Adaptive Levels is my favorite tool in the suite outside the standard kit. It learns support and resistance the way price actually proves it, scoring every level across four timeframes so brighter lines mean stronger levels and an expanding cloud shows where buying or selling should step in. In the guide I read the strength ratings on the Nasdaq, put the tool through a real test on TSLA, and walk through the settings, with the anchor date being the only one you will need to adjust per asset.
Also this week
News
The stories that moved names on our radar.
Amodei, Altman, and Musk All Said Slow Down: What It Means for the AI Trade · Sep 13
Anthropic CEO Dario Amodei published an essay calling on the AI industry to slow down, and Sam Altman and Elon Musk backed it the same day; Altman also confirmed OpenAI will not IPO in 2026. Nothing in the essay cuts chip or capex demand directly, since the one line that would, limiting training compute, is floated rather than proposed. The real risk heading into the week is sentiment, not fundamentals, with a Fed hike expected, the 10-year near 5%, and AI multiples already compressed.
Copper Miners Fell 6% to 9%: The Tariff Premium Is Coming Out · Sep 10
Reuters reported that the White House plan for a 15% tariff on refined copper, rising to 30% in 2028, has stalled on affordability concerns ahead of the midterms, and Freeport, Southern Copper, and COPX fell 6% to 9% on the news. That tariff is why 696,000 metric tons sit in Comex warehouses, more than double LME and Shanghai combined, so removing it as a catalyst matters. For the trade to come back we need a firm policy decision either way, China's imports turning up, and the dollar and hike odds backing off.
Midterm Odds Are 50/50 on a Democratic Sweep and Stocks Are Priced for
Gridlock · Sep 10
Polymarket has a Democratic sweep of both chambers at 50%, a split Congress at 36%, and a GOP sweep at 14%, but stocks are priced for gridlock. The rally is resting on four assumptions holding simultaneously: no landing, no Fed hike, no AI capex cut, and no Democratic sweep. A sweep points to higher taxes, more regulation, and less political capital behind the AI buildout, with the playbook calling for stocks down 10% or more, a weaker dollar, and lower yields into year-end. With PPI running hot, the ECB hiking, and the Fed and BoJ likely to follow, the contrarian trade I find most interesting here is Treasuries.
Earnings Reports
Every earnings print I covered this week, linked to the full post.
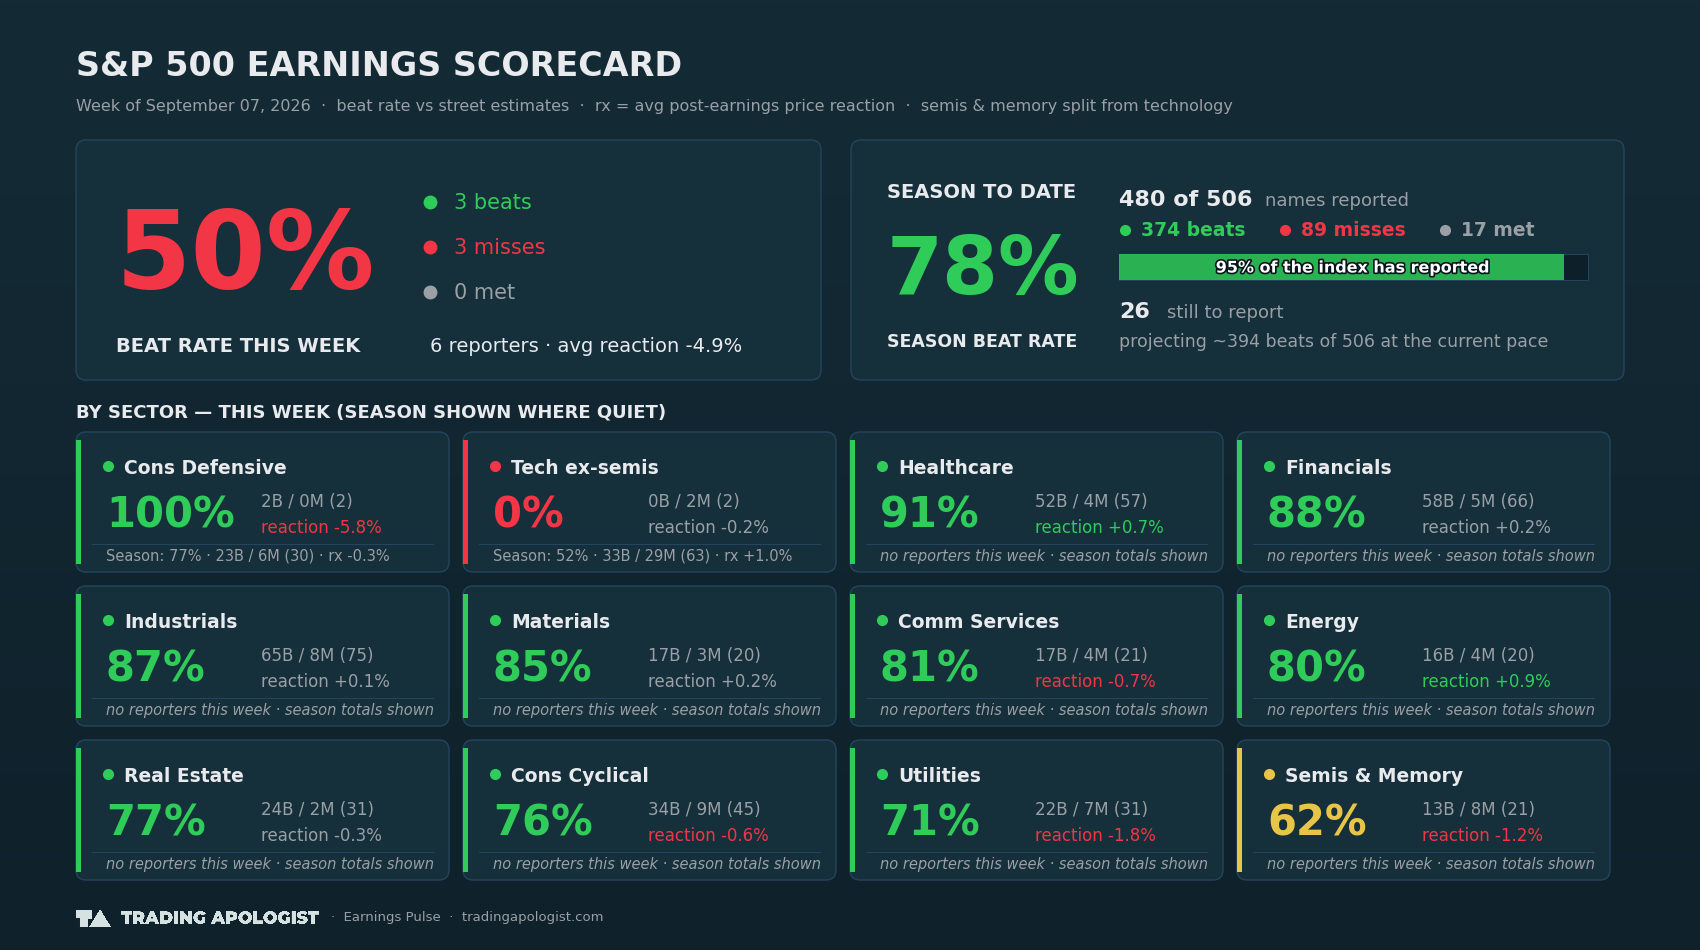
This week we had 6 reporters and a 50% beat rate, with 3 beats and 3 misses. The tape treated reporters poorly, with the average price reaction at -4.9%.
Consumer Defensive was the strongest sector at 100% with an average reaction of -5.8% across 2 reporters. Tech ex semis was the weakest at 0% with an average reaction of -0.2% across 2 reporters, and that mix does not really line up with the longer run pattern where beats have generally been rewarded less than you might expect.
Not a member? You are seeing the free weekly summary. Join the Patreon to read the full posts.