Trading Apologist
The Weekly Market Digest · Sunday, September 20, 2026
Hi everyone,
I hope you had a solid weekend and got some time to step away from the screens. Before the next trading week gets going, here is a look back at everything we covered over the past seven days.
The week in brief
It was a heavy week, and the Fed was the center of gravity for almost all of it. The Fed hiked to 4% in a unanimous vote, dropped the supply shock language, and signaled at least one more rate hike is coming, which touched everything from sector rotation to margin costs to what long-term Treasuries do next. Layered on top of that was a Saudi oil cutoff to Europe, persisting Middle East tensions, a Bank of Japan hike to its highest rate since 1995, and a retail sales beat that we dug into carefully to separate real demand from price effects. On the regulatory side, crypto had a genuinely consequential week with the CLARITY Act failing in the Senate, the House crypto tax bill advancing, and the SEC approving onchain trading of tokenized stocks, and we broke each of those down in separate posts. If you want to go deeper on the tools side, the AI Trade Desk guides and Zoom call recording covering Supercharts, Deep Reads, and Pairs and Rotation dropped this week, and Trader and Quant members just had their free 3- and 7-day trials start today. As for the week ahead, Monday and Tuesday are going to be about seeing how the market follows through on the positive Friday close, now that the massive options expiry and index rebalancing are behind us.
It was a heavy week, and the Fed was the center of gravity for almost all of it. The Fed hiked to 4% in a unanimous vote, dropped the supply shock language, and signaled at least one more rate hike is coming, which touched everything from sector rotation to margin costs to what long-term Treasuries do next. Layered on top of that was a Saudi oil cutoff to Europe, persisting Middle East tensions, a Bank of Japan hike to its highest rate since 1995, and a retail sales beat that we dug into carefully to separate real demand from price effects. On the regulatory side, crypto had a genuinely consequential week with the CLARITY Act failing in the Senate, the House crypto tax bill advancing, and the SEC approving onchain trading of tokenized stocks, and we broke each of those down in separate posts. If you want to go deeper on the tools side, the AI Trade Desk guides and Zoom call recording covering Supercharts, Deep Reads, and Pairs and Rotation dropped this week, and Trader and Quant members just had their free 3- and 7-day trials start today. As for the week ahead, Monday and Tuesday are going to be about seeing how the market follows through on the positive Friday close, now that the massive options expiry and index rebalancing are behind us.
Asset Watch
Single-name setups worth a look.
Asset Watch: QCOM & MediaTek - MediaTek Ships the First 2nm Phone Chip · Sep 16
MediaTek launched the Dimensity 9600 Pro, the first phone chip on TSMC's 2nm process, with phones shipping this quarter, and its market cap has passed Qualcomm's at roughly $235 billion versus $200 billion. Qualcomm answers at the Snapdragon Summit September 22 to 24, where two new flagship chips are confirmed and a 2nm process is reported, and its stronger story right now is outside phones: the Amazon custom AI chip deal, the Volkswagen supply agreement, and the US iPhone 18 Pro Max modem.
Asset Watch: IBM - Anderon Quantum Foundry Locks In $1 Billion CHIPS Award · Sep 16
Anderon, IBM's standalone quantum chip foundry in Albany, finalized its $1 billion CHIPS Act award, with IBM matching it for $2 billion total and first wafers already running through the line. IBM sold off about 3% on the news to near $241, but the award was proposed in May and the stock jumped 11% then, so today's move was mostly priced in. The real test is Q3 earnings in October.
The Weekly Alpha
The week's flagship posts: the market recap, the live calls, and the watchlist review.
Weekly Trade Recap - 9/14 - 9/18 · Sep 20
Ten trades across nine names this week, almost all of it managing existing positions after Wednesday's Fed-driven drop broke swing lows across several holdings. I rolled GOOGL calls, averaged down on COPX and JD, rolled JOBY down a strike, and trimmed a small slice of QCOM, among other moves. I held most names through the break because I expect a bounce, and I will have more on sector rate sensitivity in a separate post.
Weekly Market Prep Zoom Call - 09.14.26 · Sep 14
We opened the weekly prep call on the overnight selloff tied to the coordinated call to slow frontier AI development, which by the open had narrowed almost entirely to AI and semiconductor names while MAGS, IBM, U, and META held up. The bigger event on the horizon was FOMC on Wednesday, and my view was that a hike is what markets can absorb while a hold or a cut could produce the sharper selloff, with a lot of charts sitting right on support heading into the decision.
Markets & Macro
The bigger picture across rates, commodities, and the tape.
Fed Hikes to 4%: Unanimous Vote, Supply Shock Excuse Dropped, One More Coming · Sep 16
The Fed raised rates a quarter point to 3.75 to 4.00% in a unanimous 12-to-0 vote, dropped the language blaming inflation on supply shocks, and the dot plot shows 16 of 18 officials expect at least one more hike this year. The 2026 median moved to 4.1% and the median does not start easing until 2028, so the cut the June dots had penciled in for next year is gone.
Fed Rate Hikes: Which Sectors Get Hurt and Which Benefit · Sep 20
The Fed's first hike since July 2023 is hitting rate-sensitive sectors hard, and the historical record across five cycles since 1994 shows real estate, consumer discretionary, staples, materials, industrials, and small caps underperform the S&P 500 most in the year after a first hike. Financials tend to be the weakest in the first three months but recover after a year, while energy, technology, health care, and communication services hold up best. The two numbers I am watching from here are the 10-year yield for utilities and real estate, and the 2-to-10 spread for banks.
Saudi Arabia Cuts Europe Off: The Full Oil Risk Map Into 2027 · Sep 18
Saudi Aramco told European refiners they will receive no crude in October after a drone strike shut the East-West pipeline on September 11, and Brent is holding around $104 to $105 with physical North Sea barrels trading above $130. Russia adds a second fuel shock, with diesel exports down roughly 81% versus the five-year average as Ukraine keeps hitting refineries. The futures curve prices December 2027 Brent near $77, so a higher target into late 2027 is a direct bet against the curve.
What the S&P 500 Does After a Fed Rate Hike: 18 Cases Since 1946 · Sep 17
The Fed raised rates a quarter point to 3.75%-4.00%, the first hike since July 2023, and I went back through all 18 rate-hike cycles since 1946 to see what the S&P 500 does next. The median path is down for the first three months and then up around 4% to 6% at six and twelve months, and hikes that land within 5% of an all-time high (where we are now) have historically produced the best forward returns. Pace is the bigger variable: slow cycles averaged roughly 10%-11% gains a year out, while fast cycles averaged a loss of about 4%.
The Five Ways Out of the US Debt Spiral, Explained · Sep 13
With the 10-year yield at its highest since 2023 and interest on the national debt running near $1 trillion a year, I laid out the five realistic exits from the debt spiral: grow out of it (the AI bet), inflate it away (the path of least political resistance and the reason gold stays bid), cap yields through Fed intervention the way the US did from 1942 to 1951, cut spending (arithmetically possible but politically nearly impossible given four of every five federal dollars go to entitlements and interest), or revalue the Treasury's gold from $42 an ounce to market for a one-stroke $1.1 trillion gain. Each path has a different winner and loser, and knowing which one is most likely shapes how you position.
Also this week
Sector Relative Strength
Week of September 14 · % change vs prior week's close
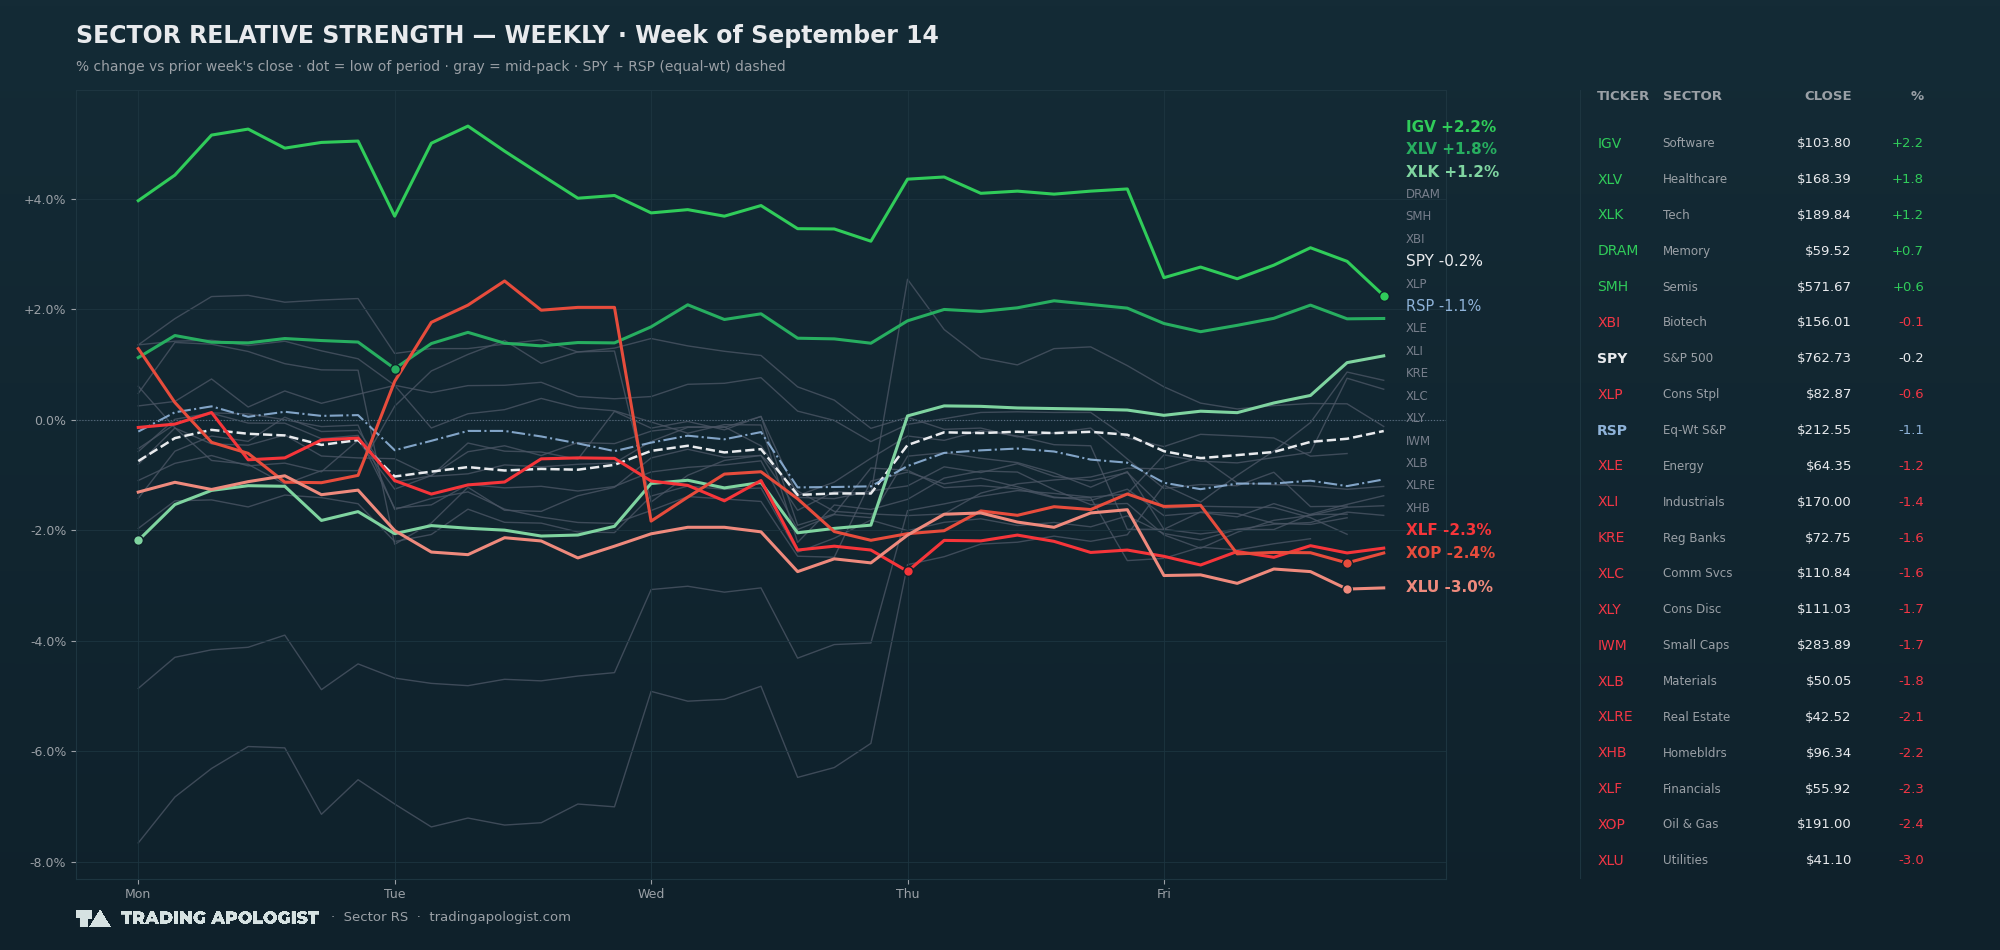
Software (IGV)+2.25%
Healthcare (XLV)+1.83%
Technology (XLK)+1.16%
Memory (DRAM)+0.71%
Semiconductors (SMH)+0.55%
Biotech (XBI)-0.12%
Cons Staples (XLP)-0.61%
Energy (XLE)-1.21%
Industrials (XLI)-1.37%
Regional Banks (KRE)-1.56%
Comm Services (XLC)-1.56%
Cons Discretionary (XLY)-1.71%
Small Caps (IWM)-1.73%
Materials (XLB)-1.77%
Real Estate (XLRE)-2.07%
Homebuilders (XHB)-2.15%
Financials (XLF)-2.32%
Oil & Gas E&P (XOP)-2.41%
Utilities (XLU)-3.04%
S&P 500 (SPY)-0.20%
Equal-weight S&P (RSP)-1.08%
Market Recaps
Every market recap from the week in one place: the daily and morning notes plus the weekly recap.
Community & Tool Updates
Indicator releases, new tools, events, and community happenings.
AI Trade Desk Zoom Recording: Supercharts, Pairs, Rotation, & Your Free Trial
Is Live · Sep 20
Miles and I hosted the AI Trade Desk Zoom this week covering what the desk actually is and how to use it. Miles has been forcing himself to trade exclusively from the desk, and every gap he finds becomes a new feature, which is why the update pace has been so fast. We walked through Supercharts, pair trading, and rotation live, and all Trader and Quant members got a free trial afterward.
AI Trade Desk Guides: Supercharts, Deep Reads, and Pairs & Rotation · Sep 13
Miles finished three in-depth AI Trade Desk guides covering Supercharts, Deep Reads, and Pairs and Rotation, each walking through a single feature start to finish on real charts. I would watch them in that order since Deep Reads and Pairs both hand off into Supercharts, but each one stands on its own.
News
The stories that moved names on our radar.
CLARITY Act Fails in the Senate 49-50: What Happened and What Comes Next · Sep 15
The CLARITY Act failed in the Senate 49 to 50, eleven votes short of the 60 needed, with zero Democrats crossing over despite months of ethics negotiations. Bitcoin fell about 4% to around $75,800, CRCL dropped 11.5%, and COIN fell 10.1%. The House leaves town Thursday, so the realistic window for a crypto market structure bill in 2026 is closed.
The SEC Just Approved Onchain Trading of Tokenized Stocks. Here Is What the
Exemption Actually Allows · Sep 17
The SEC issued a five-year innovation exemption letting onchain venues trade tokenized versions of US-listed stocks without an exchange license, and liquidity providers to supply those pools without a dealer license. The exemption is narrower than the headline: tokens must carry real dividends and voting rights, issuers can block their stock, and trading halts whenever the primary market halts. COIN and HOOD are up 2% to 3% after falling hard on the Fed hike.
House Committee Passes the Crypto Tax Bill 38-5: Wash Sales Now Dated
September 14 · Sep 16
The House Ways and Means Committee passed the Digital Asset Tax Certainty Act 38 to 5, with most Democrats voting yes, and one important update: the wash sale rule is now dated to sales after September 14, 2026, meaning any loss-and-rebuy trade from that day forward is already caught if the bill becomes law. The bill heads to the House floor next.
Also this week
The Strategic Bitcoin Reserve Bill Clears Its First Vote: 20-Year Lock, Annual
Audits, No Buying Yet · Sep 17
Earnings Reports
Every earnings print I covered this week, linked to the full post.
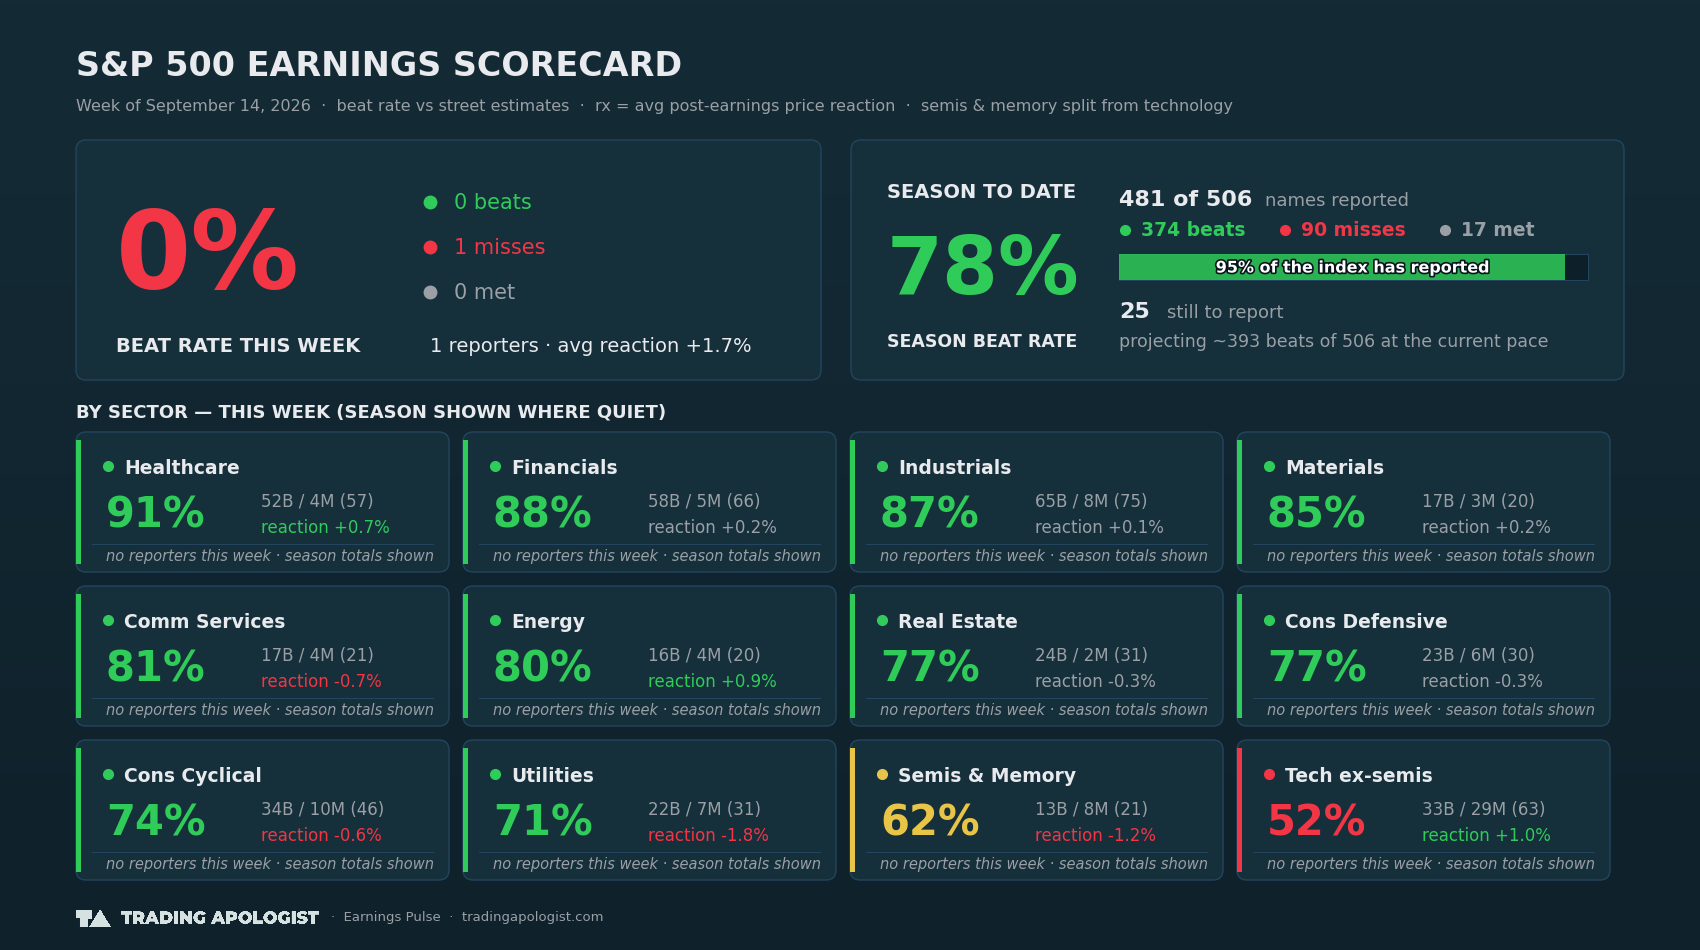
Only one company reported this week, so the scorecard stats are more noise than signal: the 0% beat rate is a single miss, not a trend, and the +1.7% average price reaction is one name's tape. We are almost to the end of earnings season, so there are no sector patterns worth calling out on a sample this thin.
Not a member? You are seeing the free weekly summary. Join the Patreon to read the full posts.