Trading Apologist
The Weekly Market Digest · Sunday, September 27, 2026
Hi everyone,
I hope you had a good weekend and got some rest. Before the new trading week gets going, I want to take a quick look back at everything we covered this past week.
The week in brief
It was a quieter week for our trades, but a fairly turbulent week in markets, despite the indices closing positive. Yields pushed to 20-year highs with October hike odds climbing to 70%, and yet the Nasdaq managed a record weekly close. That tells us a lot about how challenging the macro is right now. The bond market was a constant theme, from a weak 5-year auction that deepened the Wednesday selloff, to mortgage rates topping 7.5%, to the MOVE index jumping over 30% at one point. In our Patreon posts and weekly Zoom call, we spent a good amount of time working through what rising rates mean for different parts of the market. Oil was another major story, with the Saudi East-West pipeline restart and Iran's Hormuz proposal taking some pressure off the input cost side of things. However, the US rejected that proposal this weekend, so oil may be right back up at the overnight open. On the earnings front, we saw a 75% beat rate from this week's reporters, but the tape was not rewarding them for it, with an average price reaction of negative 1.4% across reporters, and Consumer Cyclical was the only sector with enough data to call out, posting a 50% beat rate and a modest positive reaction. This coming week we get back into more consequential earnings, with MU reporting on Wednesday, which will begin to move the tape more for our trades in DRAM, SNDK, and broader semiconductor names. Despite all the challenges in the macro, the indices are holding up well, so we remain in an environment where letting price structure lead the decision making remains the best strategy. We should see some volatility this coming week with end-of-quarter rebalancing, and from there we will see whether the anticipated Q4 rally arrives on schedule or after a bit more chop.
It was a quieter week for our trades, but a fairly turbulent week in markets, despite the indices closing positive. Yields pushed to 20-year highs with October hike odds climbing to 70%, and yet the Nasdaq managed a record weekly close. That tells us a lot about how challenging the macro is right now. The bond market was a constant theme, from a weak 5-year auction that deepened the Wednesday selloff, to mortgage rates topping 7.5%, to the MOVE index jumping over 30% at one point. In our Patreon posts and weekly Zoom call, we spent a good amount of time working through what rising rates mean for different parts of the market. Oil was another major story, with the Saudi East-West pipeline restart and Iran's Hormuz proposal taking some pressure off the input cost side of things. However, the US rejected that proposal this weekend, so oil may be right back up at the overnight open. On the earnings front, we saw a 75% beat rate from this week's reporters, but the tape was not rewarding them for it, with an average price reaction of negative 1.4% across reporters, and Consumer Cyclical was the only sector with enough data to call out, posting a 50% beat rate and a modest positive reaction. This coming week we get back into more consequential earnings, with MU reporting on Wednesday, which will begin to move the tape more for our trades in DRAM, SNDK, and broader semiconductor names. Despite all the challenges in the macro, the indices are holding up well, so we remain in an environment where letting price structure lead the decision making remains the best strategy. We should see some volatility this coming week with end-of-quarter rebalancing, and from there we will see whether the anticipated Q4 rally arrives on schedule or after a bit more chop.
Asset Watch
Single-name setups worth a look.
Asset Watch: U - Meta's AI Game Builder Hits Unity · Sep 24
Meta launched two AI game-building tools at its Connect conference that let anyone describe a game in plain language and get back a complete, playable result, and Unity fell as much as 10% on the news. This is Unity's second AI scare this year after Google's Project Genie sent it down 24% in January. Meta's tools go further than Genie, but they build games for Meta's own apps rather than the studios that actually pay Unity.
Asset Watch: AKAM Lands $11.6 Billion Anthropic Deal · Sep 24
Akamai signed a seven-year, $11.6 billion cloud deal with Anthropic after the bell, with room to grow to roughly $20 billion, and the stock popped more than 30% in after-hours trading after closing down almost 6%. Anthropic also received a warrant for up to about 5% of Akamai at $111.33 a share, tying its upside directly to the stock. I was trying to sell some of my call contracts in the final hour and am very glad those orders did not fill.
Asset Watch: Bitcoin · Sep 21
Bitcoin made a higher swing high this week, clearing the May high near $82,600 and trading near $85,000 for the first time since late January. That structural shift means any pullback from here will most likely make a higher low, and the June low now looks like the bear market bottom with high confidence. The most important signal is on the weekly chart, where the RSI broke out from its downtrend.
Also this week
The Weekly Alpha
The week's flagship posts: the market recap, the live calls, and the watchlist review.
Weekly Trade Recap - 9/21 - 9/25 · Sep 26
Only four trades went through this week across four names, and three were position management rather than new ideas. The more important part of the video is the extreme breadth reading we are seeing with the market within 1% of all-time highs. I took the breadth indicator back to the dot-com and GFC eras, where the same pattern played out: breadth stayed very low while price kept rising for a long time, with the dot-com case running nearly a full year before price broke a swing low. The takeaway is not that we are about to roll over.
Weekly Market Prep Zoom Call - 9/22/26 · Sep 22
We moved this week's call to Tuesday morning so we could see whether Friday's price action would follow through after triple witching and the index rebalance, and the answer was a clear enough yes that most of the call focused on what changes now. Chips had already been moving for five sessions before the META news and did not take the FOMC dip the rest of the market did, so the buying into Friday's close included deliberate positioning choices beyond mechanical rebalancing. The second key theme was that markets are rallying despite conditions that historically would have pressured them, and we discussed what that tells us about the underlying bid.
Markets & Macro
The bigger picture across rates, commodities, and the tape.
S&P 500 vs. the Bond Market: Bears Have the Evidence, Price Has the Vote · Sep 26
The 10-year Treasury yield hit 5.225% this week, oil stayed above $90, and the VIX held near 15 even as bond volatility jumped to a three-month high. Deutsche Bank's read is that the yield rise is mostly driven by growth expectations rather than inflation fears, which is a different kind of problem for the market. Small caps are showing the pressure, and breadth still needs to confirm before the rally can be fully trusted.
S&P 500 Advance-Decline Line Breaks Below Its 200-Day · Sep 24
The S&P 500 advance-decline line closed below its 200-day moving average for the first time since November 2023, a signal that has historically led to either a selloff bottom or choppy, lower markets before an eventual move higher. This one arrived with the S&P 500 about 2% below its record, making it most like the 2015 episode. Our Q4 view still calls for a rally around the turn of the quarter, but if this break does not turn out to be a bottom, expect more chop first with a rally starting closer to the midterms.
US Flash PMI: Why Strong Growth Became Bad News for Markets This Morning · Sep 23
S&P Global's flash PMI jumped to 58.4, the fastest US business growth since July 2021, and markets sold off on the news. Input costs rose at their fastest pace in four years, the 10-year Treasury pushed back above 5%, the 2-year broke higher, and the dollar hit a seven-week high. Polymarket now puts the odds of a Fed hike on October 28 at 54%, so what looked like good economic news is being read as bad news for rates and stocks.
Also this week
Sector Relative Strength
Week of September 21 · % change vs prior week's close
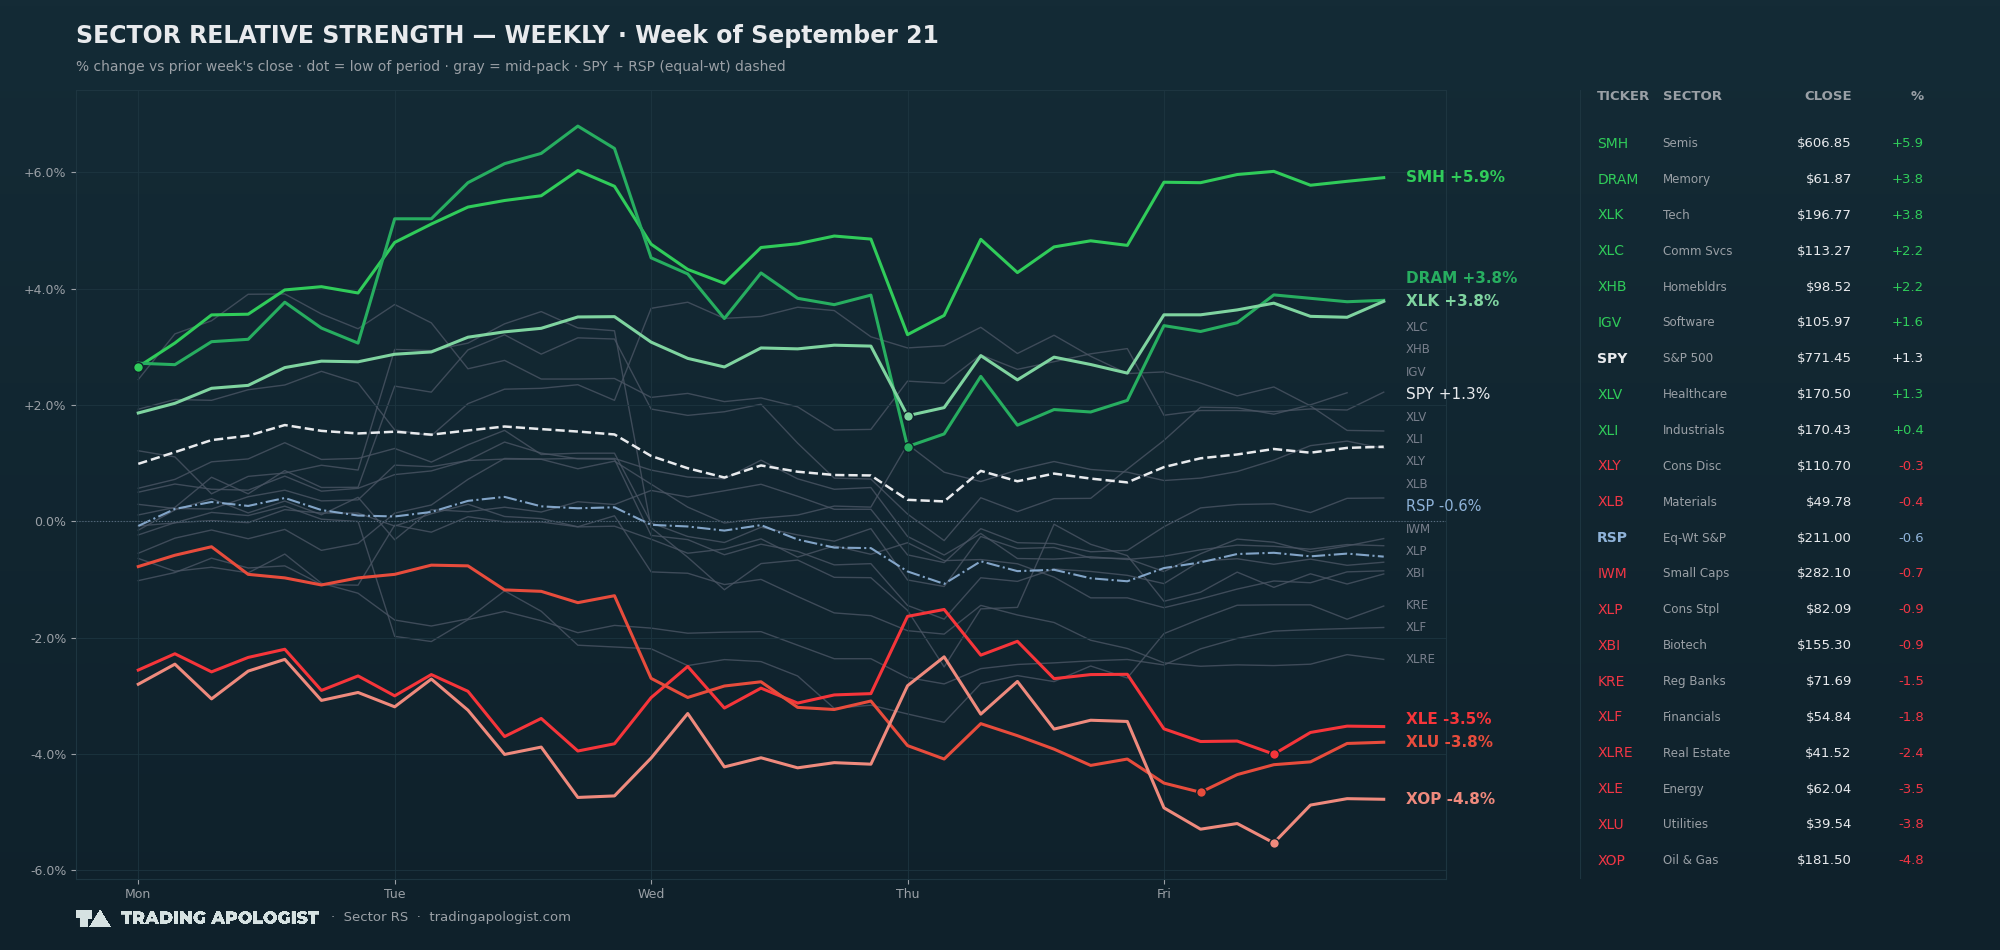
Semiconductors (SMH)+5.91%
Memory (DRAM)+3.80%
Technology (XLK)+3.78%
Comm Services (XLC)+2.22%
Homebuilders (XHB)+2.21%
Software (IGV)+1.55%
Healthcare (XLV)+1.25%
Industrials (XLI)+0.40%
Cons Discretionary (XLY)-0.30%
Materials (XLB)-0.42%
Small Caps (IWM)-0.70%
Cons Staples (XLP)-0.85%
Biotech (XBI)-0.91%
Regional Banks (KRE)-1.46%
Financials (XLF)-1.83%
Real Estate (XLRE)-2.37%
Energy (XLE)-3.53%
Utilities (XLU)-3.80%
Oil & Gas E&P (XOP)-4.78%
S&P 500 (SPY)+1.28%
Equal-weight S&P (RSP)-0.61%
Market Recaps
Every market recap from the week in one place: the daily and morning notes plus the weekly recap.
Overview Weekly Market Recap - Sept. 25, 2026
Community & Tool Updates
Indicator releases, new tools, events, and community happenings.
AI Trading Desk User Guides & Trial Extension 🙏 · Sep 22
Miles added user guides for all the primary Supercharts indicators in the AI Trade Desk, and everyone who has been a member since day one has had their free trial extended to one week for Trader members and two weeks for Quant members. We have also upgraded all APIs for faster data, lower latency, and higher rate limits. Please be brutal with your feedback as you test things out.
AI Trade Desk Zoom Recording: Supercharts, Pairs, Rotation, & Your Free Trial Is Live · Sep 20
Miles and I hosted the AI Trade Desk Zoom last Sunday covering what the desk actually is and how to use it. Miles has been forcing himself to trade exclusively from the desk, and every gap he finds becomes a new feature, which is why the update pace has been so fast. We walked through Supercharts, pair trading, and rotation live, and all Trader and Quant members got a free trial afterward.
News
The stories that moved names on our radar.
Meta's Muse Outpaces ChatGPT's Launch, and Semiconductors Take the Hint · Sep 21
Meta closed up 11.4% this week at $741.25, its best session in over a year, after third-party data showed Muse hit 1.8 million iOS downloads in its first 12 days in the US and Canada, ahead of ChatGPT's own launch pace. Chips ran with it: SMH closed up 4.02%, AMD up 9.95% and through a $1 trillion market cap, Intel up 12.17%, Arm up 17.16%, and the Nasdaq Composite closed at a record. The chart confirms a double bottom measuring to $870 to $920 on Meta.
AI Capex Returns: Goldman Puts a Price on the Hyperscaler Buildout · Sep 26
Goldman Sachs calculated that six US hyperscalers need roughly $1.42 trillion in revenue between 2028 and 2030 just to earn a 15% return on their $1.73 trillion in AI spending this year and next. Cloud backlogs at Amazon, Microsoft, and Alphabet already cover about 59% of what those three need, but the math only holds if chip rental and AI token prices stay up, and token prices just hit a record low. The model also leaves out roughly $3 trillion in off-balance sheet commitments and the $4 trillion spending phase that follows.
Trump-Xi Summit Extends the US-China Trade Truce to January 10 · Sep 25
The Trump-Xi summit produced one concrete result: a two-month extension of the US-China trade truce to January 10, 2027, which is shorter than markets expected. Tariffs did not change, the proposed Board of Trade still has no published details, and China brought only government officials rather than business leaders, which Barclays reads as a sign Beijing was not there to make deals. Barclays summed it up well: guardrails, not solutions.
Also this week
Meta Muse Shopping Agent: Amazon Blocks It, Google Search Ads Are Exposed, and
Chips Stand to Gain · Sep 24
Hester Peirce Wants to End Mass KYC Data Collection: What It Means for Crypto
Holders and ZEC · Sep 25
Earnings Reports
Every earnings print I covered this week, linked to the full post.
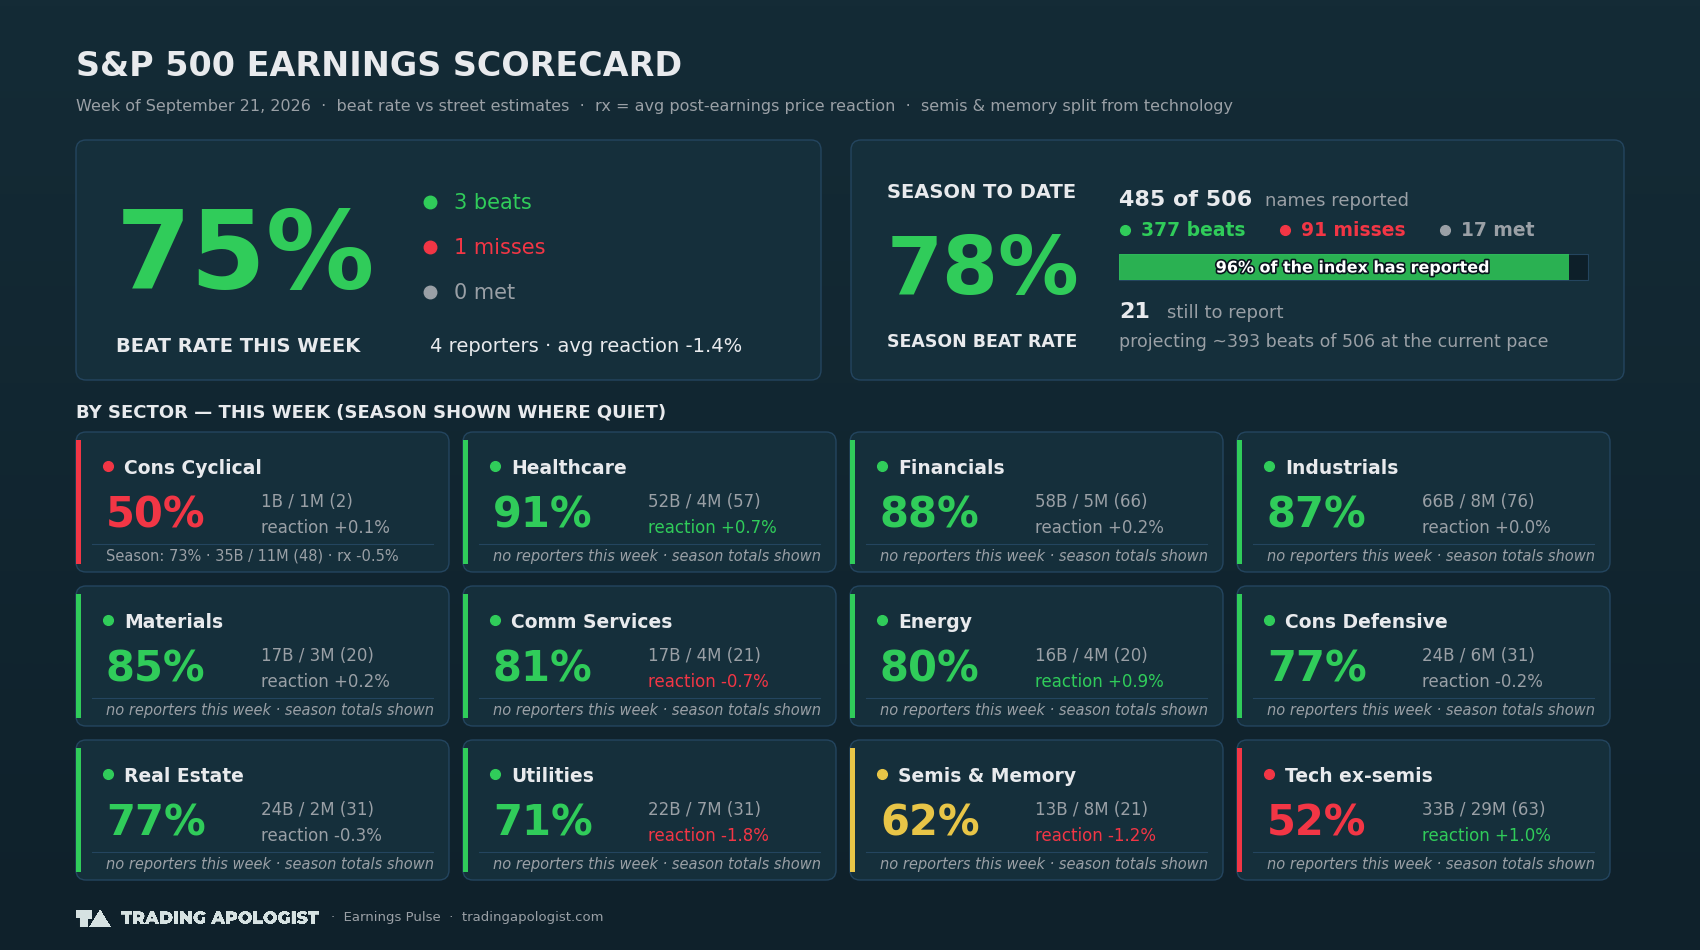
This week we saw a 75% beat rate with 3 beats and 1 miss, and the tape treated reporters pretty poorly with an average price reaction of -1.4%.
The strongest sector was Cons Cyclical at a 50% beat rate with a +0.1% average reaction across 2 reporters, and that was also the weakest showing this week since no other sector data was given. That is not really in line with the longer run pattern, which has been better overall than this week’s tape reaction.
Not a member? You are seeing the free weekly summary. Join the Patreon to read the full posts.