Trading Apologist
The Weekly Market Digest · Sunday, October 25, 2026
Hi everyone,
Thank you all for your kind words, support, and patience during this challenging week. It truly means a lot, and I look forward to getting back to business as usual once the dust settles a bit more. Regardless, markets don't stop, so here is a look back at the most important topics we covered this week before the new trading week starts.
The week in brief
The big theme this week was the AI trade continuing to unravel while most of the market quietly moved higher underneath it. The S&P closed Friday below its ascending triangle after a second breakdown following a failed breakout, but 330 of roughly 500 names in the index rose on the week, the equal weight gained about 1.1%, and money rotated into energy, staples, utilities, healthcare, and financials rather than leaving the market altogether. Earnings added texture to that picture: 75 companies reported with an 80% beat rate, and the tape rewarded them with an average price reaction of plus 0.8%, but the market was selective, with energy and industrials leading the way while semis and memory dropped 5.5% and comm services fell 3.0% despite clean beats. The pressure is coming from the details inside the reports, not the headline numbers, and heading into the week ahead I am watching whether the S&P can hold here or sets up a move toward the next logical support level, how the rotation into value and defensives holds up, and whether the geopolitical backdrop around Iran and oil stays in the price or fades.
Looking ahead, next week packs the heaviest macro and earnings stretch of the quarter into four sessions. The Fed's rate decision lands Wednesday afternoon, Microsoft and Alphabet report after that same close, Amazon follows Thursday, and Apple reports the Monday after. Keep a close eye on the chip and memory names after the issues around Lam Research this past week: Seagate kicks it off Tuesday, KLA reports Wednesday, and Intel and Sandisk land Thursday. With the midterms falling the very next Tuesday, how markets digest this run will set the tone for November, and we will be covering each piece as it hits.
Asset Watch
Single-name setups worth a look.
Asset Watch: MRNA, The Numbers We Were Waiting For Leaked Early · Oct 22
Moderna dropped as much as 25% after Phase 3 results for its personalized melanoma vaccine with Merck leaked online two days before the planned ESMO presentation, then recovered nearly half the drop by the close. The confirmed numbers showed a 42% reduction in recurrence or death versus Keytruda alone, below the 49% the Phase 2b study had set as the benchmark the stock was trading on. With MRNA up more than 500% on the year and printing a fresh 52-week high the day before, expectations had no room for a miss.
Asset Watch: RBTX, BlackRock’s New Active Robotics ETF · Oct 21
BlackRock launched RBTX, its first actively managed robotics ETF, on NYSE Arca with a 0.65% expense ratio and a starting portfolio of 38 stocks run by the same team behind its $14 billion AI ETF BAI. The top five holdings are TSLA, AMD, NVDA, CGNX, and SPCX, with 57% in technology and 22% in industrials, and it includes private-market exposure through SpaceX that index rivals like ROBO and BOTZ cannot offer. Robotics has had a rough stretch since June, but I think the theme has its moment coming over the next few years.
Asset Watch: MSTR, How Long and How Hard the MSCI Pressure Lasts · Oct 17
MSCI finalized new non-operating company rules and Strategy fails its own May simulation screens, with the removal list due November 11 and index fund selling hitting after the close on November 30. MSTR fell 9.56% on Friday to $136.83 on heavy volume, rejecting from the $150 neckline that has now flipped to resistance, though the Nasdaq was also down 2.14% on the day. Forced selling estimates range from Strategy's 3.1% of shares to JPMorgan's $2.8 billion figure, and nothing here delists MSTR, touches STRC, or forces Strategy to sell Bitcoin.
The Weekly Alpha
The week's flagship posts: the market recap, the live calls, and the watchlist review.
Weekly Trade Recap - 10/19 - 10/23 · Oct 24
We ran 14 trades across 12 names this week, with the theme being cutting weekly RSI breakdowns on the AI and growth side of the book. I locked in profits on IBM $250 calls and took a quarter of the VIX hedge off into Thursday's extreme move, then rolled the remainder out to December to keep protection on. Small adds went into beaten-down names like POET, DRAM, ALB, TE, and COPX looking for a recovery bounce, and IBIT came back into the book after last week's exit.
Weekly Market Prep Zoom Call - 10.19.26 · Oct 19
On the market prep call this week we covered the AI Trade Desk's new Volatility Adjusted Yield indicator and the expanded morning briefs for Pro tier members, plus an update from TradingView suggesting existing indicator subscribers will keep access without an added charge under the new creator platform structure. We also discussed the week's macro setup across AI, chips, and the broader tape, and I flagged that my father was not doing well and my travel plans for the week might shift depending on his doctors appointments.
Markets & Macro
The bigger picture across rates, commodities, and the tape.
Why Money Is Rotating From Tech to Value: France’s Bond Market, Hormuz, and a Capex Cut · Oct 23
The Nasdaq fell 2.6% and the semiconductor index dropped 6.7%, while the equal-weight S&P 500 rose 0.7% and the Dow finished flat: money moved, it did not leave. Three pressures drove the rotation: a leveraged French bond trade unwinding with the France-Germany spread at 2011 levels, renewed Iran escalation with US embassies emptying out, and Tesla becoming the first major AI spender to cut capex. The 10-year Treasury yield fell back below 5%, putting a bid under homebuilders, staples, healthcare, and regional banks.
Trump Says Iran Strikes Could Come Sunday: What is Moving Oil, Bitcoin, and the Weekend Tape · Oct 25
Trump said Saturday the US could strike Iran 'maybe tomorrow,' but it was a week of Houthi attacks on Saudi infrastructure that pushed Brent to $116.72, its highest close since April. Bitcoin broke below $80,000 with roughly $820 million in leveraged positions liquidated, and Trump signed a Defense Production Act memo declaring oil production essential to national defense, opening federal money for refineries and fuel storage. Ukraine hitting Omsk again kept Russian fuel supply under pressure just as Washington was leaning on Russian diesel to cool US prices.
Hedge Funds Lost on Both Sides of the AI Trade on Thursday · Oct 24
Goldman Sachs prime brokerage data showed all three main hedge fund strategies lost more than 1% on Thursday, the first time that has happened on a single day since the Covid crash in 2020. Funds got hit on both sides: AI longs fell and crowded shorts squeezed at the same time, with gross leverage near a five-year high amplifying a 1.2% S&P drop into a 2.7% loss for tech-focused funds and a 1.9% loss for multi-strategy platforms. More than two-thirds of funds in Goldman's book finished the day in the red.
Also this week
Sector Relative Strength
Week of October 19 · % change vs prior week's close
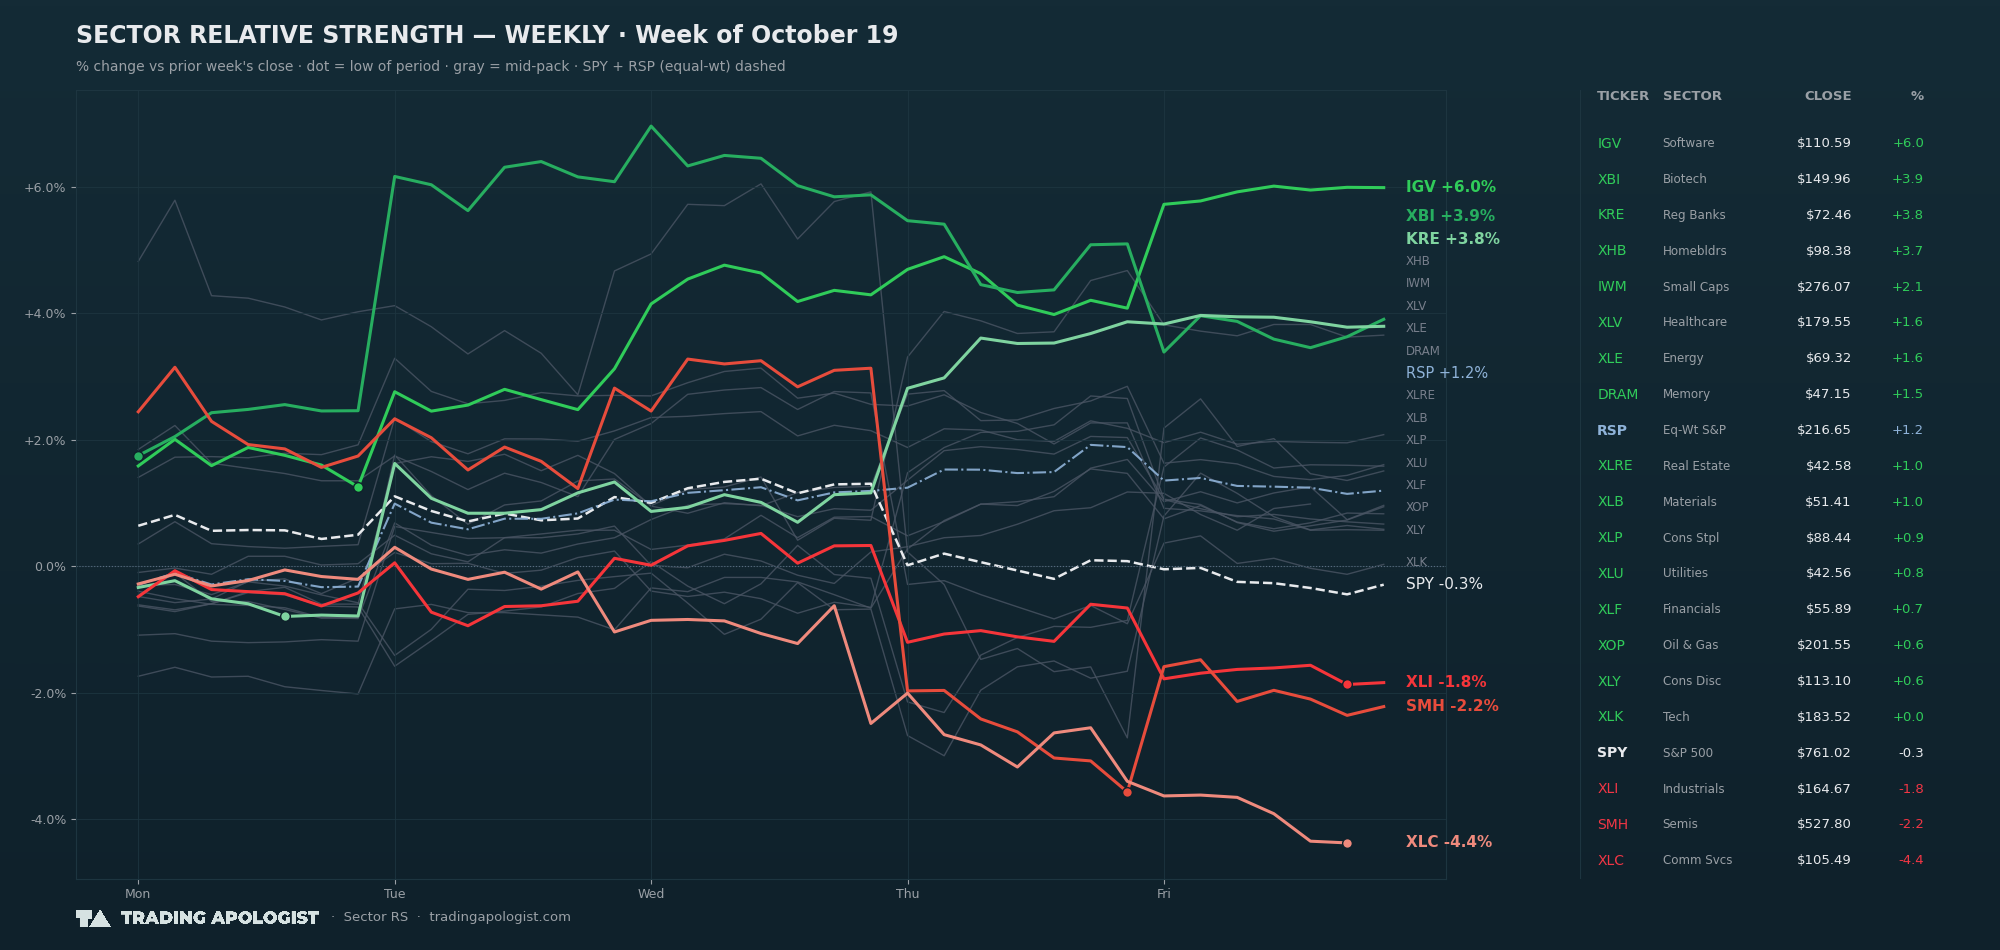
Software (IGV)+5.99%
Biotech (XBI)+3.91%
Regional Banks (KRE)+3.80%
Homebuilders (XHB)+3.66%
Small Caps (IWM)+2.08%
Healthcare (XLV)+1.61%
Energy (XLE)+1.58%
Memory (DRAM)+1.51%
Real Estate (XLRE)+0.98%
Materials (XLB)+0.96%
Cons Staples (XLP)+0.94%
Utilities (XLU)+0.83%
Financials (XLF)+0.67%
Oil & Gas E&P (XOP)+0.58%
Cons Discretionary (XLY)+0.57%
Technology (XLK)+0.03%
Industrials (XLI)-1.84%
Semiconductors (SMH)-2.22%
Comm Services (XLC)-4.38%
S&P 500 (SPY)-0.29%
Equal-weight S&P (RSP)+1.20%
Market Recaps
Every market recap from the week in one place: the daily and morning notes plus the weekly recap.
Overview Weekly Market Recap - Oct 23, 2026
Community & Tool Updates
Indicator releases, new tools, events, and community happenings.
Taking a Few Days Away · Oct 20
My father passed away, and I am traveling to be with my family. Posting will be lighter than usual for the next several days, and I will get a short note out if something truly important develops in the markets. Thank you for your patience and for being part of this community.
Weekly Market Prep: Chart Requests & Q&A · Oct 24
The live market prep Zoom call was canceled this week, but a recorded market prep video was planned for after the weekly crypto close and overnight futures open. If you had chart requests or questions you wanted covered, the comments section of the post was the place to leave them.
AI Trade Desk Update: Import Blacklist and Faster Equity Ticks · Oct 24
Miles shipped a small AI Trade Desk update this week. The main addition is an import blacklist: add a symbol once and every future broker sync and portfolio import skips it across all your connected platforms. Supercharts also got a speed bump, with equity prices now updating twice as often so charts move more closely with the live tape.
News
The stories that moved names on our radar.
Why Lam Research’s Supply Constraint Line Is Weighing on the Whole Market · Oct 22
Lam Research's supply chain constraint warning means the company cannot build and ship as many chip-making machines as customers have ordered because key parts are in short supply, not because demand has softened. The revenue did not disappear: Lam said it slides into the March quarter, and nothing was canceled. We walked through why that single line on the earnings call was enough to drag the whole chip sector lower, since Lam's machines sit at the center of nearly every advanced fab build.
Ken Griffin Calls AI a Bubble While Chamath Puts Numbers on It · Oct 21
Ken Griffin said investors are almost certainly in an AI bubble while staying long-term bullish on the technology, and Chamath Palihapitiya put rough numbers on it: by his count roughly 70 to 75 cents of every AI dollar is venture capital passing through unprofitable startups to model providers and cloud vendors. The post treats it as a revenue quality question rather than a demand question, with early AWS as the precedent for how that kind of customer base clears out before the real business arrives.
PHP2Shell: Governments Pull Websites Offline as AI-Discovered Flaw Hits 70% of the Internet · Oct 22
Two critical flaws in PHP, named PHP2Shell and discovered by frontier AI models, let attackers take over a web server with a single request and no login required. PHP runs roughly 70% of the world's websites, details leaked Tuesday, and Cloudflare was seeing active attacks before emergency patches shipped. Finland, the Netherlands, France, and Denmark pulled government sites offline as a precaution, and cybersecurity stocks including Okta, Zscaler, Cloudflare, and CrowdStrike rallied on the news.
Also this week
Pre-Earnings Report: SMCI · Oct 21
Earnings Reports
Every earnings print I covered this week, linked to the full post.
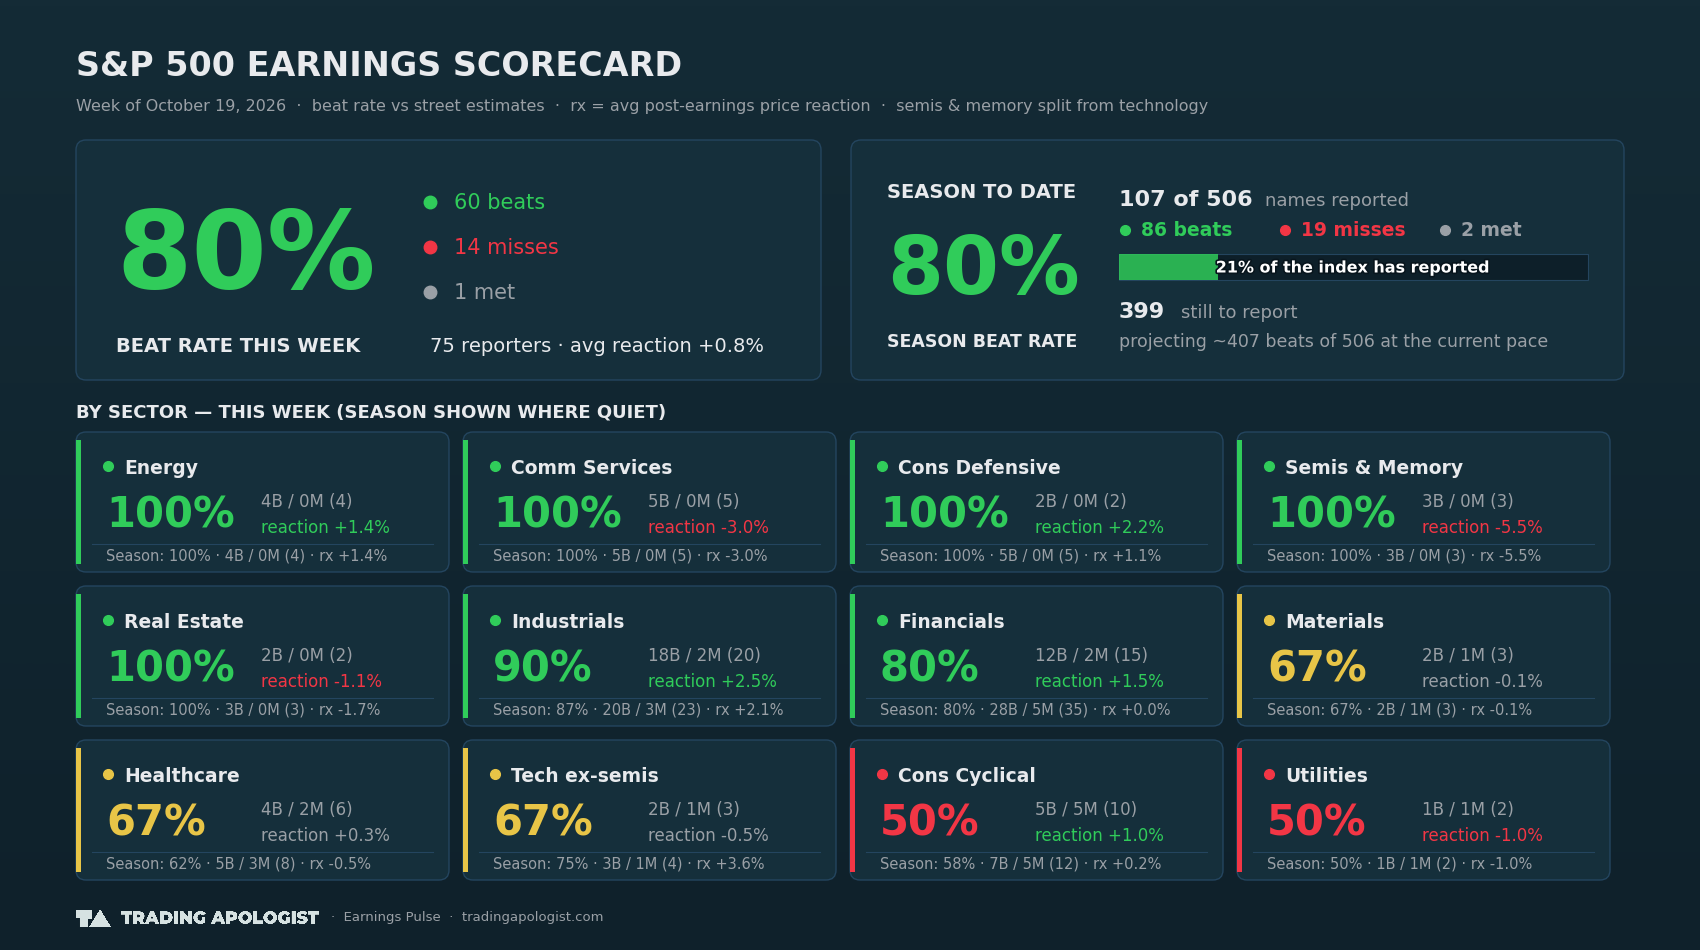
This week 75 reporters posted an 80% beat rate with 60 beats, 14 misses, and 1 in line with estimates. The tape rewarded them with an average price reaction of +0.8%, so overall it was a positive response to earnings.
The strongest groups were Energy and Cons Defensive at 100% with +1.4% and +2.2%, while Industrials also stood out at 90% and +2.5%. The weakest were Semis & Memory at 100% but -5.5%, Comm Services at 100% and -3.0%, and Real Estate at 100% and -1.1%. That mix fits the longer run pattern only partly, since the broad beat rate is solid but the market is still selective and willing to punish some high quality results.
Not a member? You are seeing the free weekly summary. Join the Patreon to read the full posts.