Trading Apologist
The Weekly Market Digest · Sunday, November 1, 2026
Hi everyone,
I hope you had a good weekend and got some time to step away from the screens. Before the next trading week gets going, here is a look back at everything we covered over the past week.
The week in brief
October closed with a narrow but aggressive selloff that landed almost entirely on the AI trade that has been carrying the market. Tech and communication services were the only major sectors down for the month, with DRAM off about 20% and SMH off over 14%, while energy, staples, and the Dow all finished higher. What drove the heavy selling was the pair of earnings from Alphabet and Amazon. Both delivered booming cloud numbers, with Google Cloud more than doubling and AWS growing at its fastest pace in nearly five years, but both also reported free cash flow swinging deeply negative as capex exploded, and both are now issuing tens of billions in bonds to fund the AI buildout. The market punished that shift from cash-funded to debt-funded spending, and rewarded Microsoft the same night for still generating positive free cash flow, but that faded later, now setting up the possibility of a double top on the MSFT chart. The biggest early tell came from hedge funds, who sold enough AI stocks in a single mid-October week to erase all of their net AI buying since the start of 2025, while retail kept buying the dip. The market is now judging every company on whether it funds its AI spending from cash flow or with debt, and is favoring value over growth for the time being. We held the 200-day moving average on the Nasdaq to close the week and SMH held RSI support, so the start of the week will be about whether those levels hold. Looking ahead, AMD earnings are the marquee report to watch, the midterms land Tuesday, and there is oil and Iran risk flagged for just after the vote, so keep an eye on whether the Nasdaq and semis hold support through it all.
October closed with a narrow but aggressive selloff that landed almost entirely on the AI trade that has been carrying the market. Tech and communication services were the only major sectors down for the month, with DRAM off about 20% and SMH off over 14%, while energy, staples, and the Dow all finished higher. What drove the heavy selling was the pair of earnings from Alphabet and Amazon. Both delivered booming cloud numbers, with Google Cloud more than doubling and AWS growing at its fastest pace in nearly five years, but both also reported free cash flow swinging deeply negative as capex exploded, and both are now issuing tens of billions in bonds to fund the AI buildout. The market punished that shift from cash-funded to debt-funded spending, and rewarded Microsoft the same night for still generating positive free cash flow, but that faded later, now setting up the possibility of a double top on the MSFT chart. The biggest early tell came from hedge funds, who sold enough AI stocks in a single mid-October week to erase all of their net AI buying since the start of 2025, while retail kept buying the dip. The market is now judging every company on whether it funds its AI spending from cash flow or with debt, and is favoring value over growth for the time being. We held the 200-day moving average on the Nasdaq to close the week and SMH held RSI support, so the start of the week will be about whether those levels hold. Looking ahead, AMD earnings are the marquee report to watch, the midterms land Tuesday, and there is oil and Iran risk flagged for just after the vote, so keep an eye on whether the Nasdaq and semis hold support through it all.
Asset Watch
Single-name setups worth a look.
Asset Watch: GOOGL - Why Alphabet Is Heavy Going Into Wednesday’s Earnings · Oct 25
Alphabet heads into Wednesday's earnings about 22% below its May high, carrying five headwinds: an $84.75 billion equity raise in June, a capital spending increase to $195 billion to $205 billion that pushed free cash flow negative, a securities lawsuit over the Gemini 3.5 Pro delay, a Finnish stop-work order on two data center sites, and a London cloud outage that took down UK banks. The whole AI complex sold off after Meta raised its spending plans last week, with 10-year yields above 5% making every dollar of the buildout more expensive. The Fed decision lands the same afternoon as earnings, making Wednesday one of the heaviest single-day setups of the year.
Asset Watch: SK Hynix (SKHY) · Oct 26
A report from Dong-A Ilbo says SK Hynix plans a special dividend of about 16 trillion won, roughly $12 billion. It is a striking show of how much cash the memory makers are throwing off right now, even as memory was the heaviest corner of the tech selloff this month.
Asset Watch: INTC - Worst Day Since 1974 on the December Quarter Guide · Oct 30
Intel fell nearly 30% this week, its worst single day since 1974, after guiding December-quarter revenue to $15 billion to $16 billion against a Wall Street expectation of $17.1 billion. PC chip revenue is guided down more than 20% as memory costs choke demand, and Intel does not expect positive free cash flow in 2027. A quick rebound that sets lower highs on Intel, Alphabet, and Amazon would be a warning sign to hedge or move into cash or defensives.
Also this week
Asset Watch: ENVX · Oct 28
The Weekly Alpha
The week's flagship posts: the market recap, the live calls, and the watchlist review.
Weekly Trade Recap - 10/26 - 10/30 · Nov 1
Eight trades across seven names this week, mostly position management as tech came under pressure into Friday. I locked in gains on IBM and AAPL, trimmed the VIX hedge on Friday's spike, added to LAC and NVDA, and started small new positions in GOOGL and CRCL. QCOM and NVDA both held support on Friday's close, so I stayed in both despite discussing exits on Discord.
Weekly Market Prep Video - 10.25.26 · Oct 26
ES futures this week are printing the same breakdown we saw on the S&P to close last week, with a lower swing low and a wick below 7,670 that still needs to confirm as a fake-out. Mean reversion is near the bottom of the range, and a shallow dip and bounce is on the table, but if support fails, 7,500 is the first solid level and the 7,200 to 7,300 zone is next. The KOSPI, SMH, and DRAM are steady and very oversold overnight, oil looks like it could be topping near its price targets, and I still think OIH comes out on top of the energy plays once stability returns.
Markets & Macro
The bigger picture across rates, commodities, and the tape.
Why the AI Trade Got Sold: Alphabet, Amazon and the Shift to Borrowing · Oct 31
Alphabet and Amazon both reported strong growth this week and both got sold hard, because both are now borrowing heavily to fund AI spending rather than paying from cash, which changes their risk profile. A new Barclays report shows default insurance on all ten major AI names has widened, with Broadcom, AMD, and Nvidia moving the most, and insurance on AI debt now costs more than the extra yield the bonds pay. That credit market signal is worth watching alongside the charts.
Fed Holds at 3.75% to 4%, Two Dissents Want Another Hike · Oct 28
The Fed held the funds rate at 3.75% to 4% this week on a 10-2 vote, with Governor Lisa Cook joining Beth Hammack in dissenting for a hike. The statement upgraded growth from 'solid' to 'strong' and left December open without promising anything. Cook's dissent is the notable development: a governor read as a steady vote for the chair just went on record that the current rate is not high enough.
October’s Selloff Was Narrow: Tech Fell, Most of the Market Rose · Oct 31
A closer look at the month shows how concentrated the damage was. Tech and communication services were the only sectors down, with memory and semis the heaviest, while energy, staples, real estate, homebuilders, regional banks, and the Dow all finished higher. Money is rotating out of the AI trade and into value rather than leaving stocks, which is healthier than a broad flush, but the indices still cannot climb without tech.
I Bonds Now Pay 5.51%: What The Treasury Is Admitting About Inflation · Nov 1
New Series I savings bonds pay 5.51% through April, up from 4.26%, with the fixed portion jumping to 1.40%, its highest since 2006. The fixed rate is effectively the Treasury putting a price on its own inflation problem, and a higher guaranteed real return on risk-free paper raises the bar for every growth stock that has to justify its price on earnings years out.
Also this week
Sector Relative Strength
Week of October 26 · % change vs prior week's close
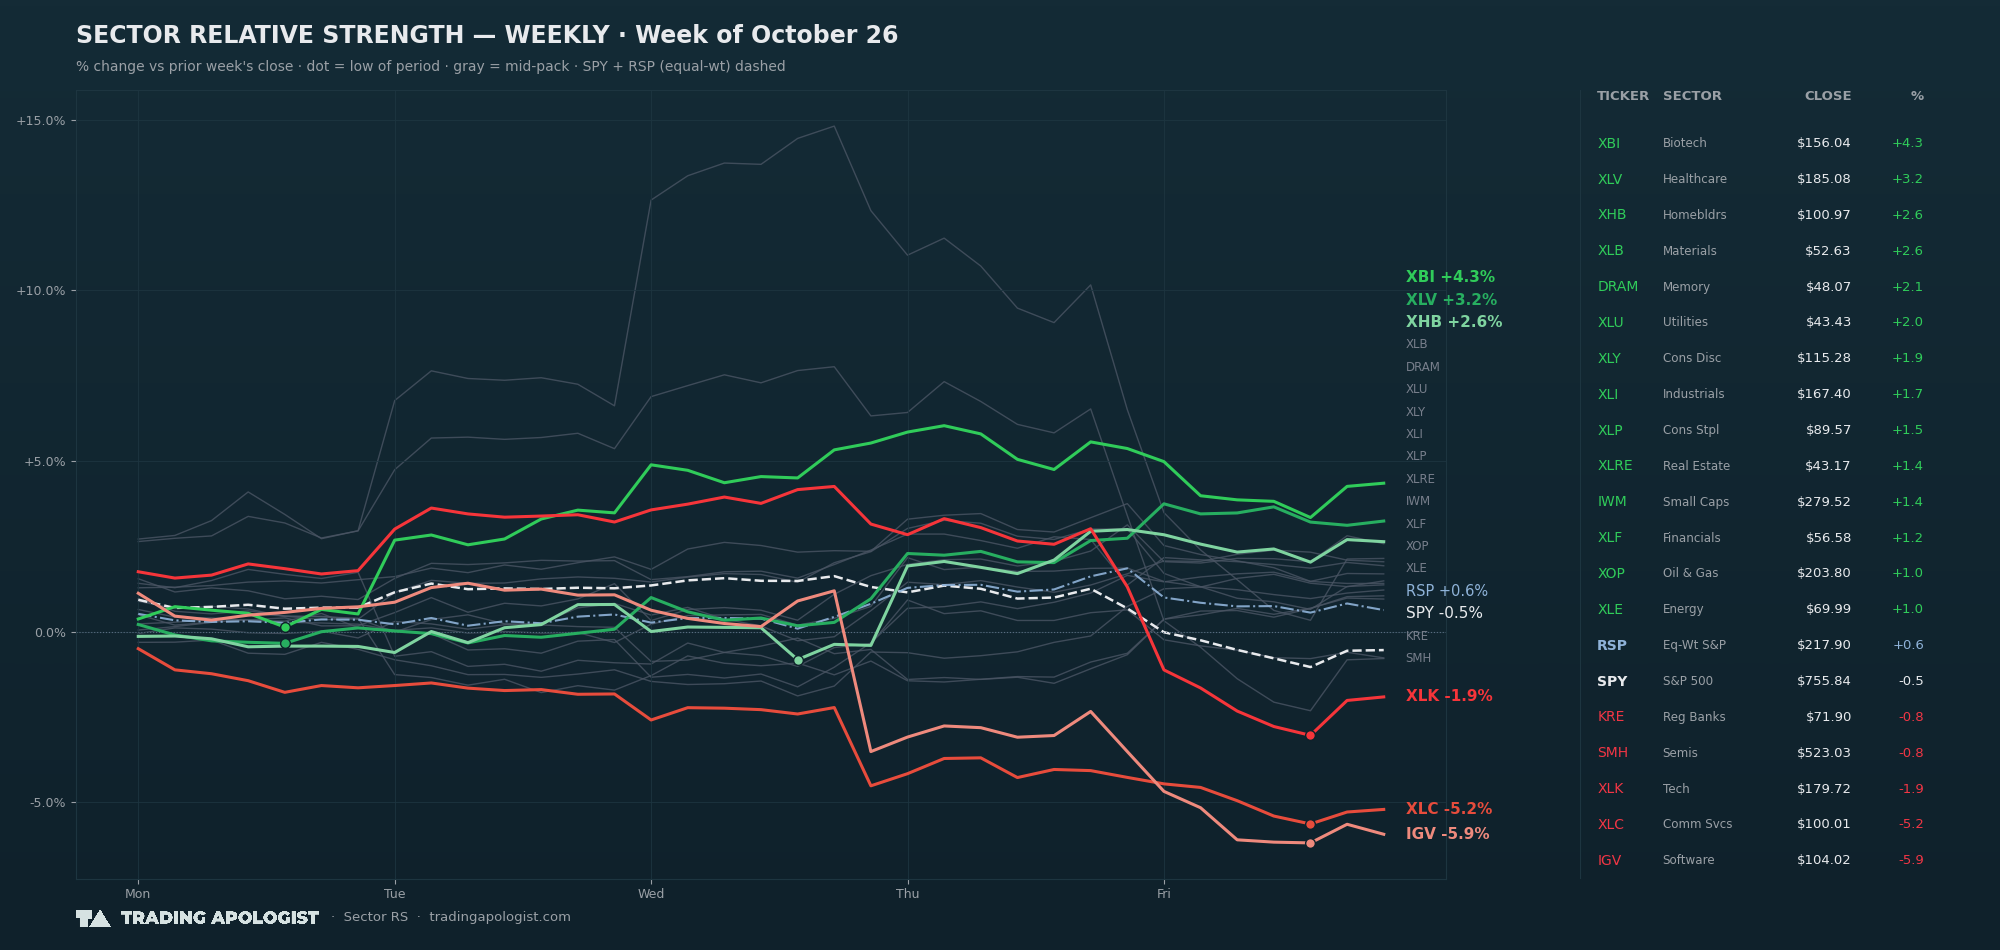
Biotech (XBI)+4.35%
Healthcare (XLV)+3.24%
Homebuilders (XHB)+2.63%
Materials (XLB)+2.57%
Memory (DRAM)+2.14%
Utilities (XLU)+2.04%
Cons Discretionary (XLY)+1.93%
Industrials (XLI)+1.69%
Cons Staples (XLP)+1.48%
Real Estate (XLRE)+1.41%
Small Caps (IWM)+1.37%
Financials (XLF)+1.22%
Oil & Gas E&P (XOP)+1.05%
Energy (XLE)+0.95%
Regional Banks (KRE)-0.77%
Semiconductors (SMH)-0.79%
Technology (XLK)-1.92%
Comm Services (XLC)-5.21%
Software (IGV)-5.94%
S&P 500 (SPY)-0.54%
Equal-weight S&P (RSP)+0.63%
Market Recaps
Every market recap from the week in one place: the daily and morning notes plus the weekly recap.
Overview Weekly Market Recap, Oct 30th 2026
Thursday Daily Market Recap - Oct 29, 2026
News
The stories that moved names on our radar.
Marvell Is in Advanced Talks to Buy Lumentum · Oct 28
Bloomberg reported that Marvell is in advanced talks to acquire Lumentum, the laser and optical supplier, a deal that would pull a key piece of the AI networking supply chain in house.
Brazil’s Runoff: Lula Wins and $EWZ Gives Back the Whole Election Rally Overnight · Oct 26
Lula won the runoff 51.8% to 48.2%, overturning Flavio Bolsonaro's first-round lead, and the Brazil ETF EWZ gave back its entire election rally overnight as the result landed.
Anthropic IPO: The Business Is Real, the Price Is a Guess · Nov 1
Anthropic's S-1 shows $16.3 billion of revenue in the first half of 2026 and a first profitable quarter, with the headline $80.7 billion net loss almost entirely a paper charge on convertible notes rather than cash burned. The harder questions are the growth that already slowed in the Q3 figures the filing leaves out and the roughly $800 billion of compute commitments stretching to 2045, against a reported listing the week of November 16 at a $1.5 to $2 trillion value.
Also this week
Earnings Reports
Every earnings print I covered this week, linked to the full post.
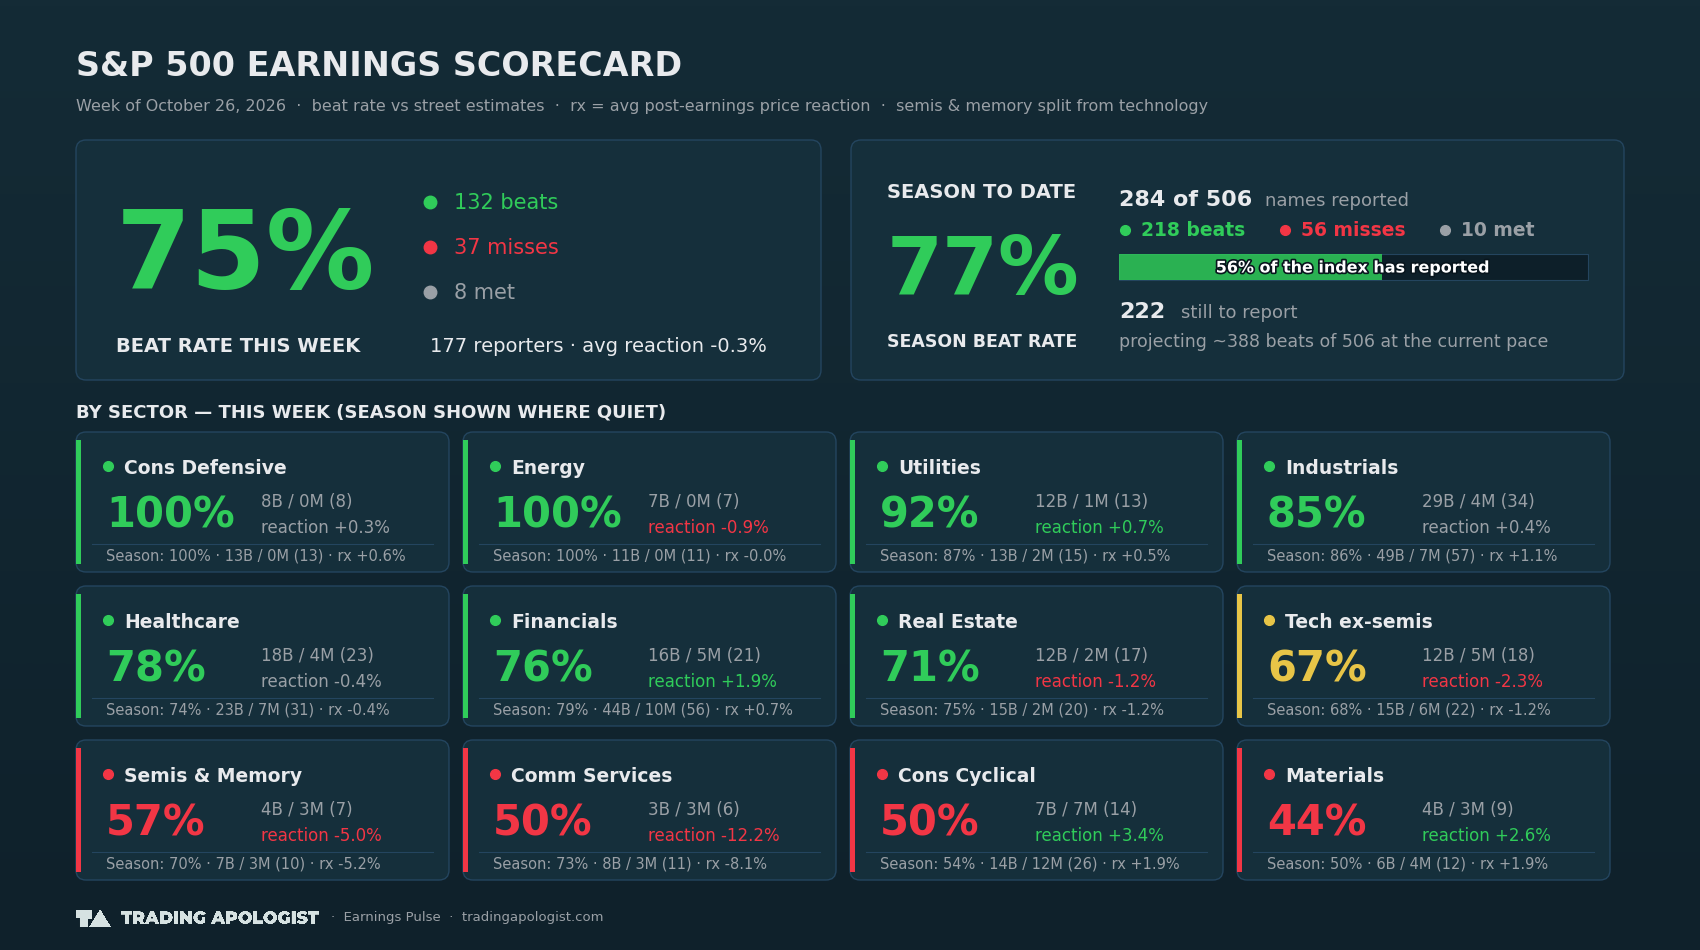
This week 177 reporters posted a 75% beat rate with 132 beats, 37 misses, and 8 in line with estimates, but the tape treated them slightly negative with an average price reaction of -0.3%.
The best responses came from Financials at 1.9%, Utilities at 0.7%, Industrials at 0.4%, and Cons Defensive at 0.3%, while the weakest were Comm Services at -12.2%, Semis and Memory at -5.0%, and Tech ex semis at -2.3%. That mix mostly fits the broader pattern of solid beats not always earning reward, with weaker reactions showing up in higher growth areas and better follow through in steadier sectors.
Not a member? You are seeing the free weekly summary. Join the Patreon to read the full posts.