Purpose
Net Premium Flow is a running total of the money committed to calls minus the money committed to puts, measured in dollars rather than contracts.
That distinction is the whole point. Contract counts are dominated by cheap, far-dated lottery tickets that cost very little and say very little. Premium is dominated by whoever actually put capital at risk. A thousand contracts at five cents and ten contracts at fifty dollars count the same by volume and differ by a factor of ten in conviction.
Best used for:
- Spotting divergence between price and where the options money is going.
- Confirming a trend: price and premium pulling the same way is agreement worth trusting.
- Reading distribution: price grinding to new highs while premium rolls over is the options-market equivalent of an OBV divergence.
- Separating real positioning from retail noise in a crowded name.
What you see on the chart
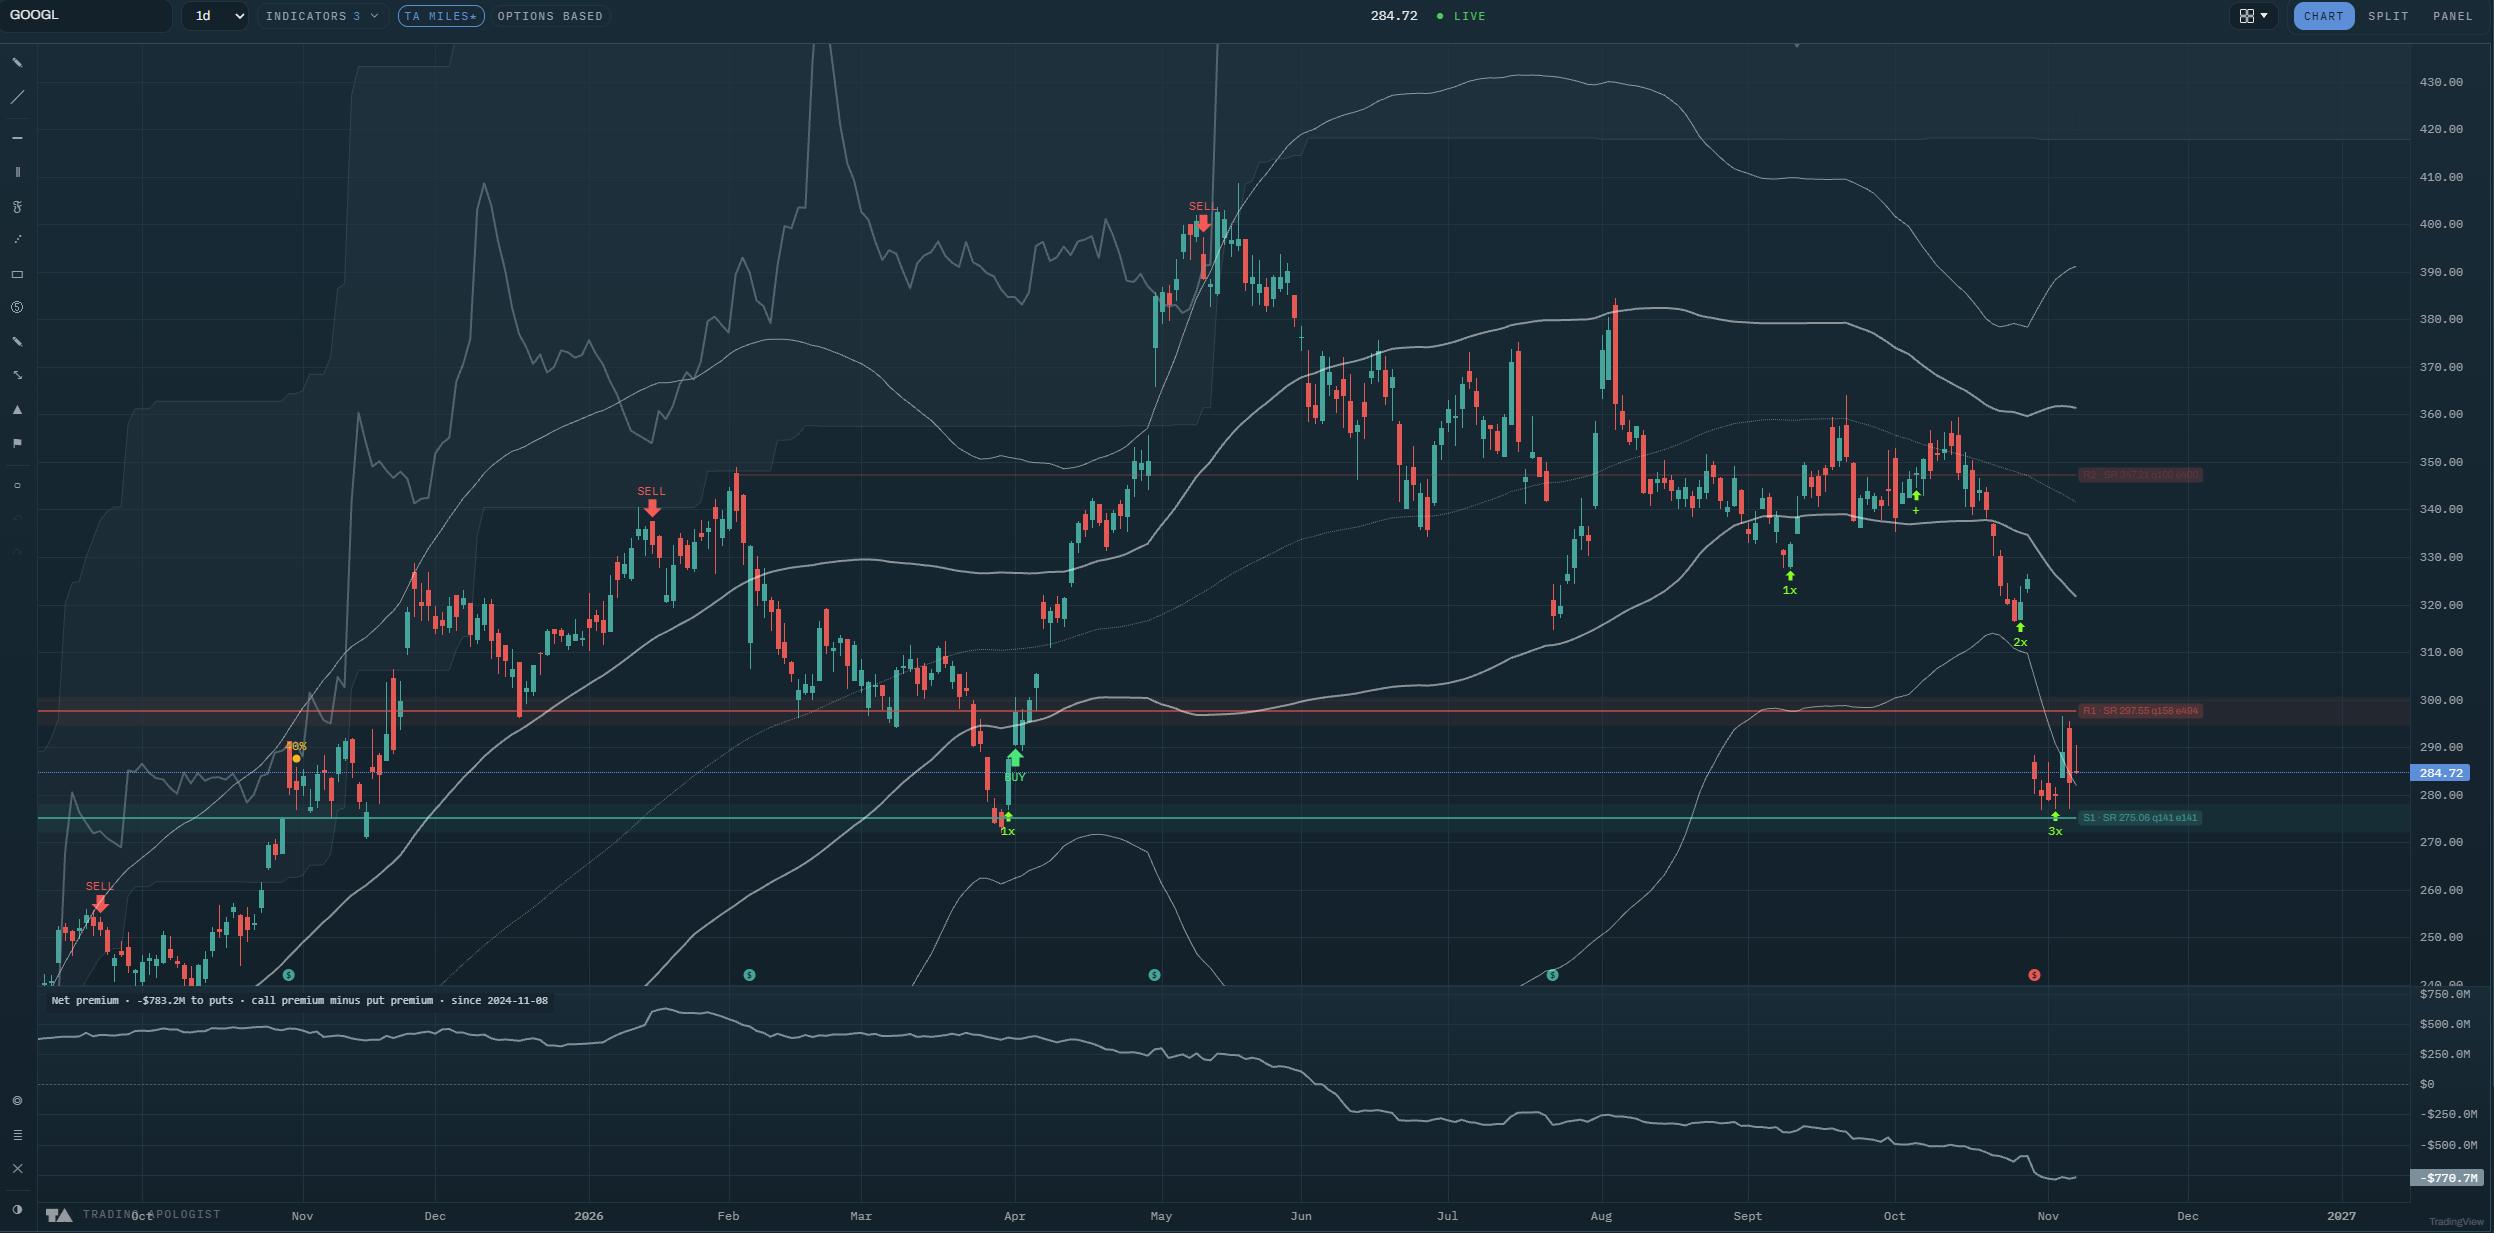
A single cumulative line in a pane below price, deliberately muted so it does not compete with the panes either side of it, with a zero line for reference.
The legend states the current total, the side it favours and which basis is drawn, for example "Net premium · -$783.2M to puts · call premium minus put premium · since 2024-11-08".
Above zero the running total favours calls; below zero it favours puts.
How to read it
- The slope matters more than the level. The total is cumulative, so its absolute value depends on how long it has been accruing. What is changing now is in the direction and steepness of the line.
- Divergence is the signal. Price making a higher high while this line makes a lower high means the money is not following the tape. It is a warning, not a timing tool.
- Agreement is confirmation. Both rising together is the simplest healthy structure: the move is being paid for.
- A sharp kink is a positioning event. Sudden steepening means a large amount of premium arrived in a short window, which is worth cross-checking against the strike gutter in Options Flow alerts.
- Zero is not special. The line crossing zero reflects where the accrual started, not a change in conditions. Read the shape, not the crossing.
How the engine works
Each day's call premium and put premium are taken from options-market totals for the symbol and subtracted, then accumulated forward from the first measured day. The legend names the anchor date so you always know what the total is measured from.
A day with no data contributes nothing and the total resumes afterwards. It is never treated as a zero, because a zero would flatten exactly the divergence the pane exists to show, and it is never interpolated, because that would invent a flow that did not happen.
Two bases are offered and both are genuine market figures, so they can disagree:
- Call premium minus put premium splits by contract type. Simple and unambiguous about what it measures.
- Bullish premium minus bearish premium splits by which side of the spread each trade hit, so a bought put counts as bearish and a sold put as bullish. Closer to intent, and dependent on the aggressor convention.
The legend always names which one is drawn, because the two can point different ways on the same day.
Honest limitation: premium tells you where capital went, not why. A large call purchase can be a bullish bet or a hedge on a short position, and nothing in the data distinguishes them. The reading is strongest in aggregate and over time, weakest on any single day.
Key settings
- Basis:
call premium minus put premiumorbullish premium minus bearish premium. - Cumulative premium: the line itself, with colour, width and line style.
Availability
US equities with a listed options chain, daily and weekly charts, on the most actively tracked names. Not available on pairs or crypto charts. Included from the Pro plan up.
Net Premium Flow is an AI Trading Desk indicator. See it on a live chart in the AI Trading Desk, or browseevery guide.
Educational and analysis purposes only. Not financial advice. See theterms.